


SBA Loan Brokers: Strategic 2026 Guide to Securing Business Capital
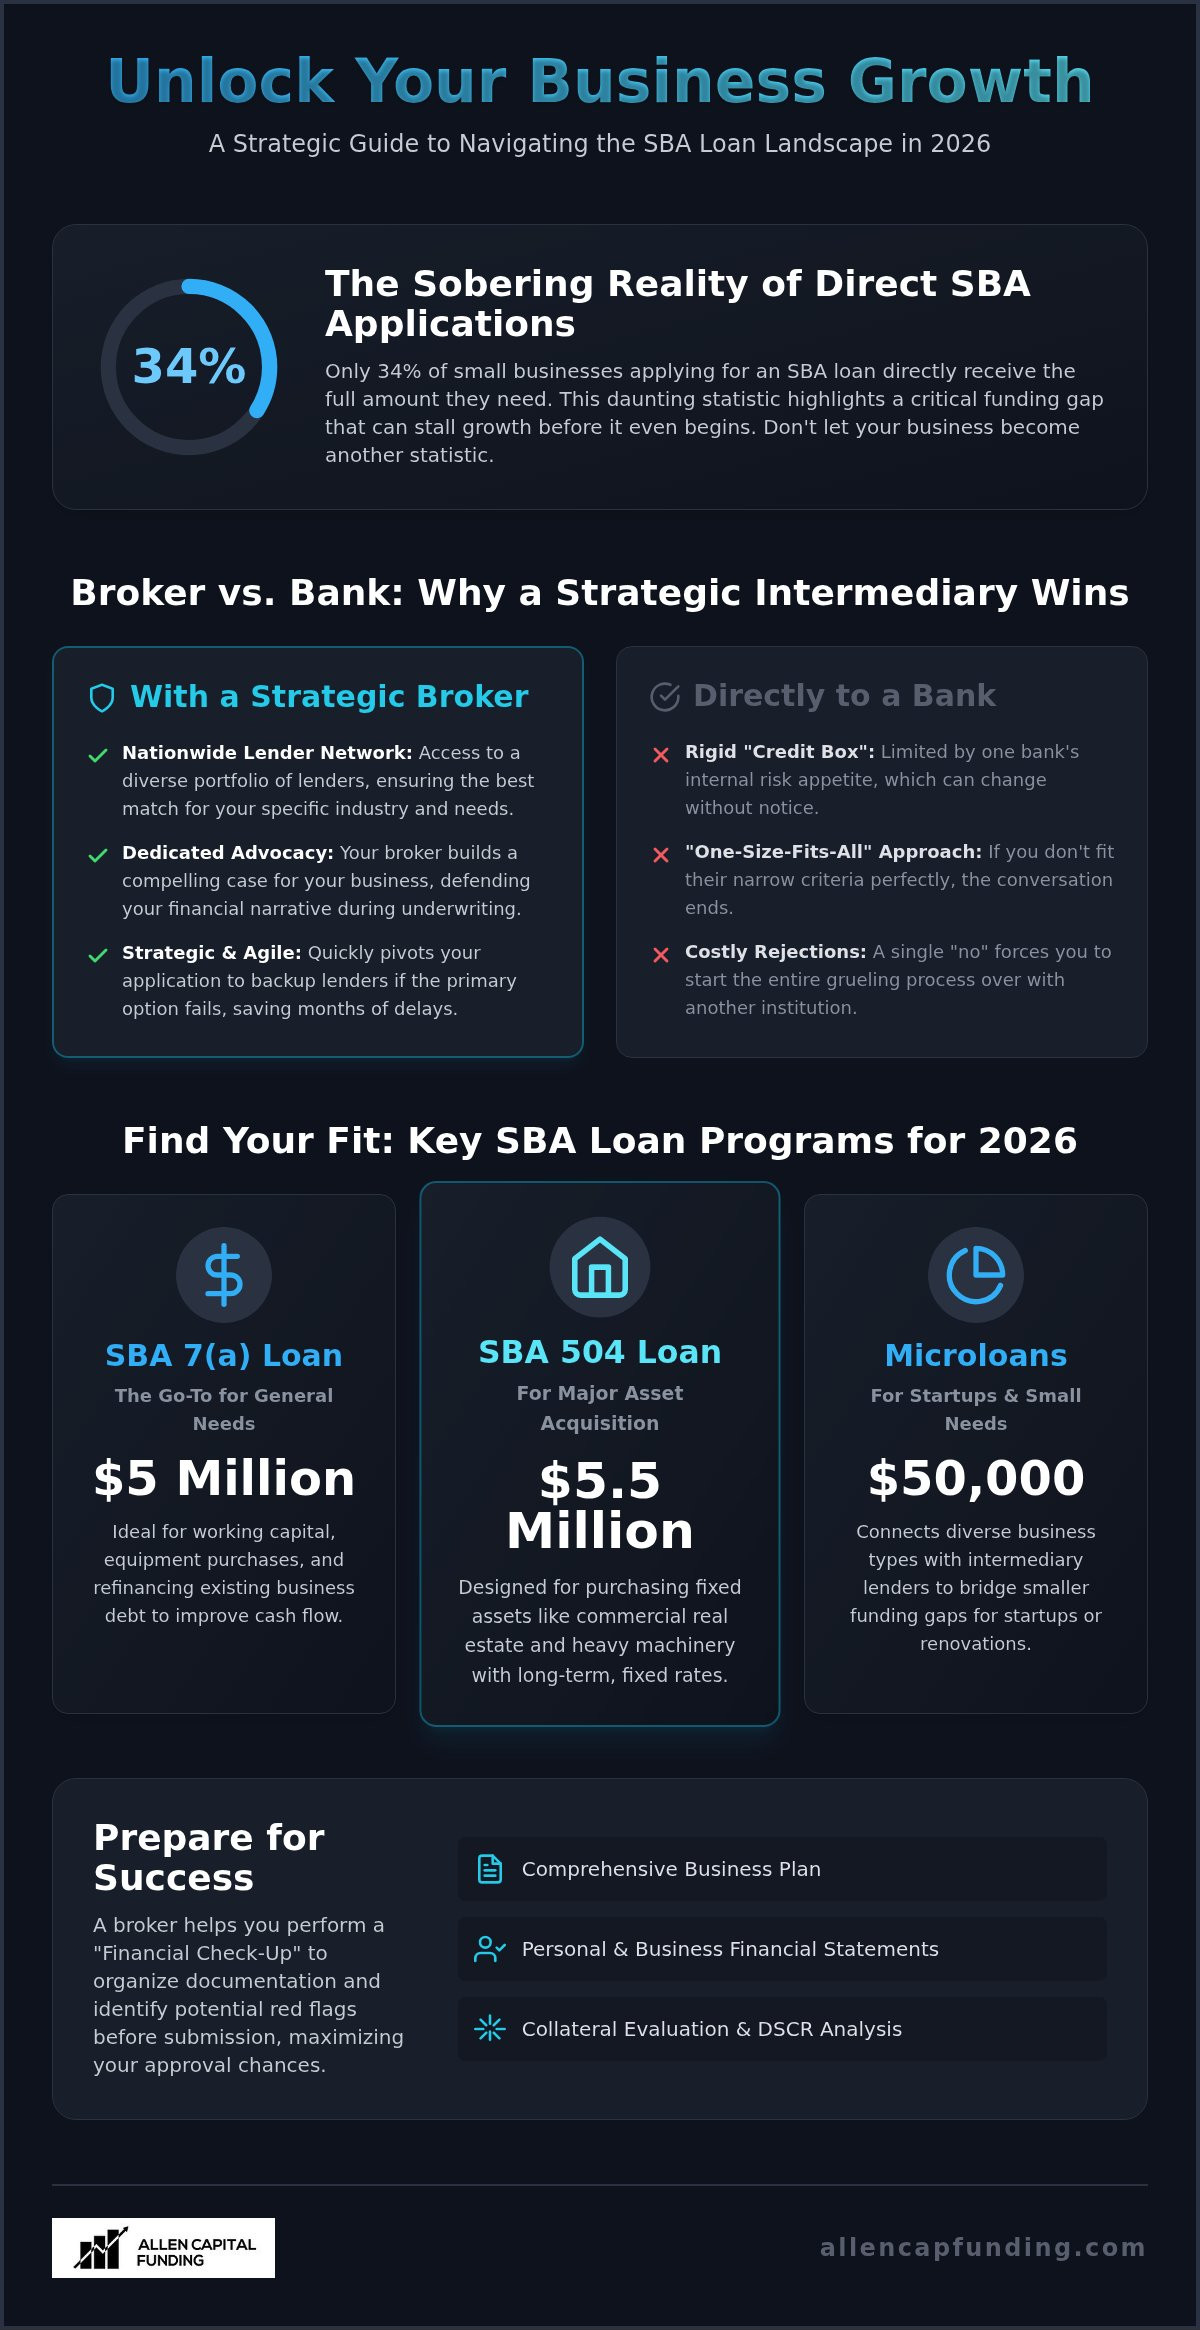
Did you know that only 34% of small businesses applying for an SBA loan actually receive the full amount they need? It's a sobering statistic that highlights why so many entrepreneurs feel overwhelmed when searching for SBA loan brokers New York. You've likely felt the weight of endless paperwork or the nagging fear that a single mistake could lead to a rejection from a traditional bank. Deciding whether an SBA 7(a) or a 504 loan fits your specific needs shouldn't feel like a high-stakes gamble when you're focused on scaling your operations.
This guide shows you how a strategic broker can transform that uncertainty into a clear path toward capital. You'll discover how a professional partner handles the heavy lifting of documentation to secure competitive interest rates and fast approvals. We'll break down the 2026 lending environment, compare the latest program limits, and explain how an expert broker acts as a strategic architect for your business growth. It's time to stop worrying about the "how" and start focusing on your next milestone.
Table of Contents
The Strategic Role of an SBA Loan Broker in 2026
Securing capital in 2026 requires more than a strong balance sheet. An SBA loan broker acts as a strategic intermediary, bridging the gap between ambitious entrepreneurs and the complex requirements of the U.S. Small Business Administration (SBA). These professionals don't just pass along paperwork; they architect a financial narrative that resonates with specialized lenders. With the SBA increasing the total combined loan limit for 7(a) and 504 programs to $10 million as of July 4, 2026, the landscape offers more flexibility than ever before. However, this increased opportunity comes with heightened regulatory scrutiny that demands expert guidance.
A standard broker might simply submit an application, but a strategic financial partner optimizes the entire loan structure. They analyze your debt service coverage ratio, evaluate collateral, and ensure your business plan aligns with current federal priorities. This high level support is vital in competitive markets where SBA loan brokers New York help businesses stand out from the crowd. By refining the application before it reaches a lender's desk, brokers significantly increase approval odds and secure terms that support long term growth rather than just providing a short term fix. They move beyond simple origination to act as your dedicated advocate throughout the underwriting process.
Why Business Owners Choose Brokers Over Direct Applications
The administrative burden of a direct application is often the primary reason for delays or rejections. Professional SBA loan brokers New York remove this barrier by handling the heavy lifting of documentation and compliance. They provide access to a nationwide network of SBA preferred lenders, ensuring your application isn't limited to the rigid criteria of a single local bank. Matching your specific needs to the right lender is a science. Brokers understand which institutions have an appetite for your specific industry or project type, saving you months of wasted effort and preventing unnecessary credit inquiries.
Key SBA Programs Handled by Professional Brokers
Brokers specialize in identifying which federal program aligns with your specific goals. They don't just offer one product; they find the right fit for your capital requirements.
SBA 7(a) Loans: This is the primary solution for working capital, equipment, and debt refinancing. In 2026, the maximum limit remains $5 million, making it the go-to for general business expansion and operational liquidity.
SBA 504 Loans: These are designed for major fixed assets and offer long term, fixed rate financing for real estate and heavy machinery. The SBA backed portion can reach $5.5 million, providing a strategic advantage for manufacturers and asset heavy firms.
Microloans: For smaller capital needs up to $50,000, brokers connect diverse business types with intermediary microlenders to bridge funding gaps for startups or smaller renovations.
Broker vs. Bank: Why Strategic Intermediaries Win
Many entrepreneurs assume going straight to a bank is the most efficient path to capital. It often isn't. Traditional lenders operate with a "one-size-fits-all" mentality. If your business doesn't fit their specific credit box, the conversation ends abruptly. In contrast, SBA loan brokers New York act as dedicated advocates who defend your financial narrative. They don't just present your file; they build a case for your success. This advocacy is crucial during underwriting when a lender might have concerns about industry-specific risks or debt-to-income ratios. Brokers understand the nuances of lender psychology. They know which bank is looking for manufacturing deals and which is cooling on retail. This insight turns a cold application into a strategic proposal that lenders want to approve.
The Limitation of Single-Bank Applications
Traditional banks are restricted by internal risk appetites. These "credit boxes" change frequently based on the bank's current portfolio balance. If a bank has too much exposure in your industry, they'll reject your application regardless of your creditworthiness. A single rejection can stall your growth for months. You're forced to start from scratch with another institution, repeating the same grueling process. Strategic SBA loan brokers New York eliminate this bottleneck. They maintain established relationships across a nationwide network of lenders. If one primary option fails, they pivot your application to a backup lender who has a higher appetite for your specific project. This speed advantage ensures your business doesn't lose momentum while waiting for a decision. Recent Federal Reserve survey data shows that only 42% of small business loan applicants received all the financing they requested. This gap exists because banks often prioritize their own internal metrics over the unique potential of a growing firm.
The Broker Advantage in Rate Negotiation
There's a common misconception that broker fees make these loans more expensive. The reality is the opposite. Brokers leverage competition among multiple lenders to secure better terms. A difference of even 0.5% in an interest rate spread can save your business thousands of dollars over a 25 year term. With the prime rate at 6.75% in September 2026, every basis point matters for your bottom line. Brokers also look beyond the interest rate. They align loan terms with your projected cash flow to ensure payments remain manageable during growth phases. This strategic alignment is a core part of a financial check-up, ensuring your capital structure supports your long-term vision. By optimizing the debt structure from the start, a broker helps you avoid the restrictive covenants that often come with direct bank applications.
How to Evaluate and Choose a National SBA Loan Broker
Selecting the right intermediary is a decision that impacts your business's capital structure for years. In 2026, a reputable national brokerage must offer more than just a list of lenders. You need a partner with a deep understanding of the current federal climate and the specific requirements of the SBA. High-quality SBA loan brokers New York stand out by providing a comprehensive "Financial Check-Up" before any application is filed. This diagnostic phase is essential to identify red flags like insufficient debt coverage or documentation gaps that could lead to an immediate rejection.
Transparency remains the foundation of a reliable partnership. A professional broker should be upfront about their fee structures and their relationships with lenders. They shouldn't hide behind jargon. Instead, they should explain how they match your business to a specific "credit box." Industry-specific expertise is equally vital. If you are a manufacturer benefiting from the 2026 fee waivers, your broker must understand how to leverage those specific NAICS code advantages to maximize your savings. They act as a facilitator, removing barriers between your current state and your future goals.
Essential Vetting Questions for Business Owners
Don't hesitate to interview your potential broker. Ask direct questions to gauge their operational depth. A high-performing broker will provide clear, data-backed answers rather than vague promises of "guaranteed approval."
What is your success rate with SBA 7(a) and 504 applications? Look for a track record of handling high-volume requests and complex deal structures that align with your funding needs.
Do you have direct access to SBA-Preferred Lenders (PLP)? PLP status allows lenders to make final credit decisions without sending the file to the SBA, significantly accelerating the funding timeline.
How do you handle complex credit profiles? A quality partner knows how to mitigate unique industry risks or minor historical credit issues through strong narrative building and strategic documentation.
Signs of a Partnership-Driven Approach
The best brokers focus on your long-term strategic growth rather than just the immediate transaction. They act as consultants who help you remove barriers to progress. This involves proactive communication and a dedicated team of specialists who manage every step of the documentation process. If an SBA loan isn't the most efficient path for your current state, a strategic partner will pivot. They might suggest Asset-Based Lending or factoring to unlock balance sheet liquidity quickly. This flexibility ensures you always have the right tool for your specific growth stage. You deserve a partner who is deeply invested in your accelerated success.
Preparing for Success: The SBA Loan Application Checklist
Securing a high-value loan requires meticulous preparation before the first document is signed. You can't simply walk into a lender's office and hope for the best. Strategic SBA loan brokers New York emphasize that a successful outcome is built in the weeks leading up to the submission. Lenders in 2026 focus heavily on stability and precision. They want to see that you understand your numbers as well as they do. This proactive preparation strategy removes the barriers to your capital and ensures your business is positioned for accelerated success.
The Financial Check-Up: Your First Step
The process starts with a comprehensive review of your debt service coverage ratio (DSCR). Lenders typically look for a DSCR of 1.25x or higher to ensure your business can comfortably handle new debt obligations. We also analyze your personal and business credit profiles to ensure they meet 2026 standards. This isn't just about the score; it's about the narrative your credit history tells. Cleaning up your balance sheets and aging reports is vital for an accurate Working Capital assessment. If your accounts receivable are lagging, it sends a signal of operational inefficiency that could stall your approval or lead to less favorable terms.
The Documentation Power-Pack
Lenders require a specific set of documents to verify your claims. Missing even one piece can delay your funding by weeks. Your documentation should include:
Tax Returns: Three years of both business and personal tax returns to demonstrate historical consistency.
Interim Financials: Profit and loss statements and balance sheets from the current fiscal year.
Aging Reports: Detailed accounts receivable and payable reports to prove liquidity.
Strategic Business Plan: A roadmap with detailed growth projections for the next 24 months.
In 2026, a generic business plan won't suffice. You need projections that account for current inflationary pressures and industry-specific trends. This proves to the lender that you're a proactive leader with a clear vision for growth.
Perfecting the Narrative
Beyond the numbers, your 'Use of Proceeds' statement must be compelling. It should clearly explain how every dollar will generate a return on investment. Whether you're purchasing real estate or expanding your team, the narrative must align with your financial projections. Finally, prepare your management team for lender interviews. Lenders aren't just investing in your business; they're investing in your leadership. Be ready to discuss your operational strengths and how you've navigated past challenges. If you want to ensure your application is lender-ready, you can schedule your strategic financial check-up today to identify and fix potential red flags early.
Navigating Complex Funding with Allen Capital Funding
Allen Capital Funding operates as a dedicated guide for entrepreneurs who need more than just a transaction. We're committed to your accelerated success. While many search for SBA loan brokers New York to simply find a lender, our approach is built on long-term partnership. We act as a facilitator, removing the complex barriers that often stand between a business and its next growth milestone. Our team moves beyond simple loan origination to provide a strategic roadmap tailored to your specific operational needs.
Why Allen Capital Funding is Your Strategic Ally
Our firm connects you to competitive capital markets through an extensive national reach. We don't limit your options to a single geographic region or one bank's rigid criteria. Instead, we leverage our network to find the most favorable terms for your unique situation. This dedicated team of specialists understands that speed and clarity are essential in 2026. We simplify the path to progress by managing the intricate details of your file, ensuring a seamless transition from the initial consultation to successful funding. You'll work with experts who focus on your specific goals rather than just checking boxes.
Beyond SBA: A Holistic Financial Strategy
A holistic financial strategy often requires more than a single product. While SBA loans provide a strong foundation, your growth might also require Equipment Financing to modernize your production line. We also help you integrate Commercial Real Estate Financing into your long-term plan to build equity and secure your physical footprint. For businesses facing immediate liquidity needs, we offer purchase order and factoring solutions that unlock cash trapped in unpaid invoices or pending orders. This breadth of solutions ensures you aren't forced into a loan that doesn't fit your business model.
Starting with a Financial Check-Up allows us to identify the best combination of products for your current state and future ambitions. We don't believe in a one-size-fits-all model. We focus on strategic advantage. Whether you're looking for working capital or a complex real estate deal, our goal is to act as your proactive ally. Book a consultation today to begin your strategic financial journey and experience the difference of a partnership-driven approach.
Secure Your Strategic Growth Capital in 2026
Navigating the complexity of federal funding doesn't have to be a solo effort. By partnering with a strategic intermediary, you move beyond the limitations of single-bank applications and gain a dedicated advocate for your growth. You've learned how a thorough preparation process and the right vetting criteria can transform your approval odds. When searching for SBA loan brokers New York, remember that the most effective partners provide expert guidance for strategic growth and a national network of SBA-preferred lenders.
Allen Capital Funding offers tailored capital solutions for every business stage, ensuring you have the right tools to remove barriers. It's time to stop guessing and start building a narrative that lenders can't ignore. Book a Strategic Consultation with Allen Capital Funding to begin your journey toward accelerated success. Your business's future depends on the strategic moves you make today. We're here to ensure you're ready for whatever comes next.
Frequently Asked Questions
What does an SBA loan broker actually do for my business?
An SBA loan broker acts as a strategic intermediary between your business and specialized lenders. They manage the heavy lifting of documentation, vet your financial health, and build a narrative that increases approval odds. By matching your needs to a lender's specific credit box, they remove barriers to capital. This approach ensures your application isn't just a number but a strategic proposal for growth.
How much do SBA loan brokers typically charge in 2026?
Brokerage fees are generally structured as a percentage of the total loan amount and are paid upon successful closing. While these costs vary based on deal complexity, they often pay for themselves through the interest rate savings secured via competitive bidding. You should always demand a transparent fee agreement before starting. These fees are regulated by SBA guidelines to ensure they remain reasonable for small business owners.
Can an SBA loan broker help if I've been rejected by my local bank?
Yes, brokers specialize in rescuing applications that didn't fit a specific bank's internal risk appetite. A single rejection often reflects a bank's current portfolio balance rather than your business's viability. Strategic SBA loan brokers New York maintain a national network of lenders with diverse requirements. They can quickly pivot your application to a partner who actively seeks your specific industry or project type, saving months of wasted effort.
What is the difference between an SBA 7(a) and an SBA 504 loan?
The 7(a) program is the primary choice for working capital, expansion, and debt refinancing with a $5 million limit. The 504 program provides long term, fixed rate financing specifically for major fixed assets like real estate or heavy machinery. As of July 2026, the combined limit for both programs has increased to $10 million. This allows businesses to secure $5 million for operations and another $5 million for property concurrently.
How long does the SBA loan process take when working with a broker?
Working with a broker typically takes between 45 and 90 days from submission to funding. While the SBA has streamlined many processes, the timeline depends heavily on the complexity of your documentation and the lender's internal review. Brokers accelerate this by ensuring your file is lender ready before it's submitted. This prevents the constant back and forth requests for missing information that often stall direct bank applications for months.
Is it better to work with a national broker or a local lender?
A national broker offers a significant advantage by providing access to a broader pool of capital than a single local institution. Local lenders are often limited by regional economic shifts or specific industry caps. A national firm connects you with specialized lenders across the country who may offer more competitive rates. This broader reach is essential for securing the best possible terms in the 2026 financial environment and supports strategic growth.
What credit score is required for an SBA loan in 2026?
Most SBA lenders look for a personal credit score of 680 or higher, though some specialized programs may consider lower scores with strong compensating factors. Lenders also evaluate your FICO SBSS score, which measures the creditworthiness of the business itself. If your score is on the margin, SBA loan brokers New York can help build a strong narrative around your cash flow and collateral to mitigate lender concerns.
Can a broker help me secure SBA funding for a business acquisition?
Brokers are essential for acquisitions because they help value the target company and structure the debt to meet SBA requirements. They ensure the deal includes enough working capital for the transition period and verify that the seller's financials are audit ready. This strategic guidance is vital for navigating the change of ownership rules that often cause delays in standard bank applications. A broker acts as your advocate during the negotiation.


Comments