


Invoice Factoring Companies New York: 2026 Strategic Funding Guide
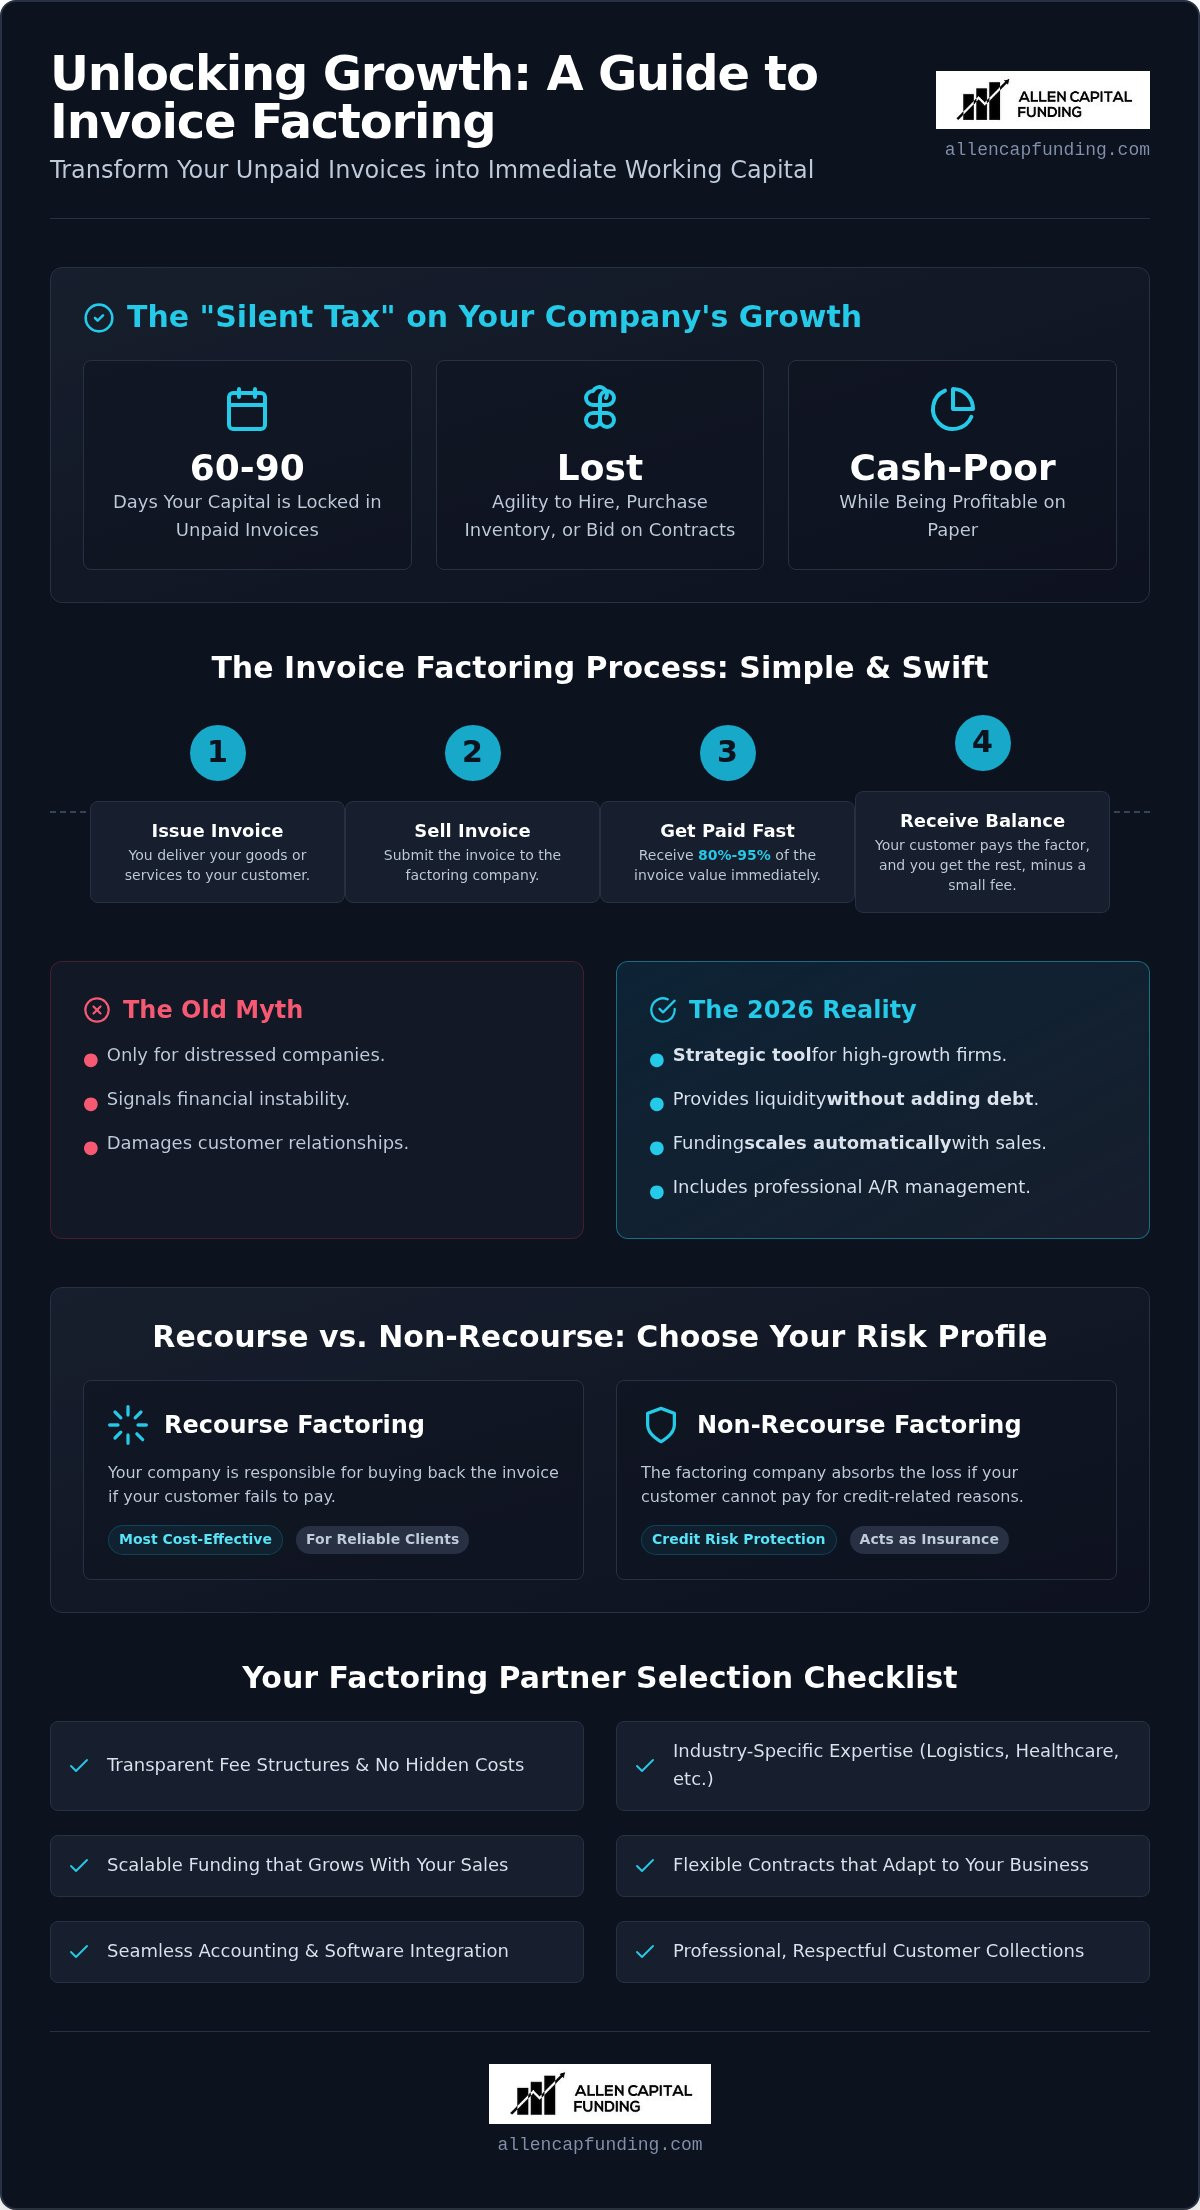
Waiting sixty days for a client to pay isn't just an inconvenience; it's a silent tax on your company's ability to scale. When your capital is locked in unpaid invoices, you lose the agility to hire, purchase inventory, or bid on larger contracts. You've likely felt the frustration of watching your bank balance stagnate while your sales pipeline overflows. It's exhausting to be profitable on paper but cash-poor in reality, especially when traditional bank loans feel out of reach or move too slowly for your pace of business.
This 2026 guide shows you how to vet invoice factoring companies new york to find a partner that treats your accounts receivable as a strategic asset rather than a debt burden. You'll discover how to unlock immediate liquidity and identify transparent fee structures that protect your margins. We'll explore the essential criteria for choosing a provider that offers seamless accounting integration and scalable funding that grows alongside your sales. By the end of this guide, you'll have a clear roadmap to transform your outstanding invoices into a reliable engine for accelerated success and sustainable growth.
Table of Contents
Understanding the Role of Invoice Factoring Companies
Invoice factoring is a straightforward financial transaction where a business sells its outstanding accounts receivable to a third party at a discount. Unlike traditional financing, this isn't about borrowing money; it's about accelerating the cash you've already earned. For many businesses searching for invoice factoring companies new york, the goal is to bridge the gap between completing a project and receiving payment from a client. This process provides immediate access to funds that would otherwise be locked in invoices for 30, 60, or even 90 days.
The perception of this tool has evolved significantly. While it was once seen as emergency funding for struggling firms, it's now viewed as strategic working capital. High-growth sectors like logistics, healthcare, and manufacturing use it to maintain operational excellence without waiting on slow payment cycles. By converting invoices into immediate funds, these companies can accept larger contracts and manage payroll with confidence. It's a facilitator that removes barriers to progress, allowing you to focus on your next milestone rather than your last bill.
The Strategic Benefits of Factoring in 2026
Modern factoring offers advantages that go beyond simple cash flow. Because it's an asset sale, it provides immediate liquidity without adding new debt to your balance sheet. This preserves your credit capacity for other needs, such as equipment financing or real estate acquisitions. One of the most powerful features is its inherent scalability. As your sales volume increases, your available funding grows automatically. You aren't restricted by a static credit limit set years ago. Additionally, many invoice factoring companies new york provide professional accounts receivable management. They handle credit checks and collections, which allows your team to focus on core business development instead of chasing payments.
Debunking Common Factoring Myths
Misconceptions often prevent business owners from utilizing this powerful resource. A common myth is that factoring is only for distressed companies. In reality, it's a preferred tool for growth-stage firms that need to move faster than a bank allows. Another concern involves customer relationships. Modern factors act as professional extensions of your back office, maintaining transparent and respectful communication with your clients. Factoring is a strategic asset-conversion tool that transforms your accounts receivable into immediate working capital rather than a traditional bank loan.
The Mechanics of Modern Receivables Financing
Understanding the flow of funds is essential for any business owner looking to optimize their cash cycle. The process begins when you deliver goods or services and issue an invoice to your customer. Instead of waiting for the payment term to expire, you submit that invoice to one of the invoice factoring companies new york businesses rely on for liquidity. The factor verifies the invoice and immediately transfers an advance, which typically ranges from 80% to 95% of the total value. This provides the instant working capital needed to cover payroll or inventory costs without the delays of traditional lending.
The remaining balance is placed into a reserve account. Once your customer pays the invoice in full, the factor releases this reserve back to you, minus a small fee known as the discount rate. This fee structure is often tiered based on how long it takes the debtor to pay. Unlike a bank loan that focuses on your personal credit score, factoring focuses on the creditworthiness of your customers. If you work with reliable, high-quality debtors, you can often secure more favorable terms regardless of your own company's financial history.
Recourse vs. Non-Recourse Factoring
Choosing the right risk profile is a critical strategic decision for your business. In a recourse agreement, your company is responsible for buying back the invoice if your customer fails to pay. This is generally the most cost-effective option and works well if your clients have a strong history of reliability. Non-recourse factoring, however, transfers the credit risk to the factor. If the debtor goes bankrupt or cannot pay for credit-related reasons, the factor absorbs the loss. While the fees for non-recourse options are slightly higher, they offer a layer of protection that serves as a form of credit insurance for your receivables.
Customer Relations and the Factoring Process
A common concern involves the Notice of Assignment (NOA). This document informs your customer that payment should be directed to the factor. While some fear this signals financial instability, it's actually a standard professional practice in modern business finance. Top-tier providers offer white glove collection services that maintain the integrity of your client relationships. They act as a professional extension of your billing department, ensuring that interactions remain courteous and efficient. To ensure you find a partner that fits your specific culture, you might consider a Financial Check-Up to evaluate which funding structure aligns best with your long-term goals.
Comparing Factoring to Other Asset-Based Solutions
Deciding between different funding options requires a clear understanding of your balance sheet. While many entrepreneurs start their search by looking for invoice factoring companies new york, they often find that combining factoring with other financial tools provides the most robust growth engine. Factoring is unique because it doesn't create debt. It converts an existing asset into cash. This makes it an excellent companion to long-term SBA loans. While an SBA loan provides capital for major expansions or real estate, factoring ensures you have the daily working capital to fulfill the orders those expansions generate. Using these tools together prevents the "growth trap" where success outpaces your cash reserves.
Factoring vs. Business Lines of Credit
A business line of credit is a flexible pool of funds, but it relies heavily on your personal credit score and historical profitability. If your business is growing faster than your credit history reflects, you might find a line of credit limit too restrictive. Factoring costs are based on a discount fee rather than an annual interest rate. This shift in focus from your credit to your customer's credit is often the deciding factor for high-growth firms. For a deeper look at these differences, review our Business Line of Credit: The Strategic Guide. It helps owners determine which structure offers the most flexibility for their specific operational cycle.
Factoring and Purchase Order Financing Synergy
Purchase order (PO) financing and factoring create a powerful synergy for companies that manufacture or distribute products. PO financing provides the capital to pay suppliers for raw materials or finished goods before you even have an invoice to sell. It's the first step in the chain. Once you deliver the product and generate an invoice, you can use factoring to pay off the PO financing and secure your profit immediately. This "capital stacking" strategy allows you to fulfill contracts that are significantly larger than your current cash reserves. It removes the glass ceiling on your growth by ensuring every stage of the transaction is funded. By leveraging invoice factoring companies new york as part of this stack, you maintain the momentum needed to scale without interruption.
Understanding these nuances is key to mastering Asset-Based Lending for Small Business and unlocking your true potential. When you view your receivables and purchase orders as strategic assets, you gain a level of control that traditional banking simply can't match. This approach doesn't just provide cash; it provides a competitive advantage in a fast-paced market.
Selection Checklist for Factoring Partners
Selecting from the vast array of invoice factoring companies new york requires a disciplined approach. You aren't just looking for a source of cash; you're looking for a long-term operational partner. The right choice can accelerate your success, while a poor fit can lead to restrictive bottlenecks. Start by evaluating industry expertise. A factor that understands the specific billing cycles of the healthcare or construction industries will be far more effective than a generalist firm. They'll know how to handle your customers' specific payment portals and documentation requirements without causing friction.
Contract flexibility is another vital metric. Many providers still use outdated "minimum volume" requirements that force you to fund more invoices than you actually need. In 2026, you should prioritize partners who offer "spot factoring" or no-minimum contracts. This allows you to use the service as a precision tool rather than a permanent overhead cost. Transparency remains the ultimate test of a factor's integrity. Always ask for a full schedule of fees, including ACH costs, wire fees, and any potential termination penalties. If these aren't clearly disclosed upfront, it's a significant red flag.
Technology integration has become a non-negotiable standard. Your factoring platform should sync directly with your accounting software, such as QuickBooks or Xero. This automation reduces manual data entry and ensures your records are always up to date. It also allows for faster verification and funding, removing the administrative burden from your internal team.
Vetting the Factor’s Financial Stability
A factor's own liquidity is the foundation of your funding reliability. If your provider faces their own capital constraints, your daily funding could be delayed, which puts your payroll and vendor payments at risk. Research the factor's reputation for consistency and timely payouts. You can often gauge this by looking at their history of serving businesses in high-demand markets. Avoid agreements with overly aggressive fine print that grants the factor excessive control over your business decisions. A supportive partner acts as a facilitator, not a micromanager.
The Importance of Speed and Accessibility
Efficiency is the primary reason businesses seek out invoice factoring companies new york. While the initial setup may take a few days for due diligence, daily operations must be rapid. In 2026, the industry standard has shifted toward a seamless 24-hour funding cycle for all verified invoices. Beyond the software, the value of a dedicated account manager cannot be overstated. When a complex billing issue arises, having a direct line to a knowledgeable expert ensures that your cash flow remains uninterrupted. To find a partner that meets these rigorous standards, explore our tailored capital solutions today.
Strategic Funding with Allen Capital Funding
Applying directly to a single lender often limits your options. If their internal criteria change or your specific industry falls out of favor, you're left without the capital you need. Working with a brokerage provides access to a vast network of invoice factoring companies new york businesses rely on for stability. We act as your dedicated advocate. Our team matches your specific needs with the lender best equipped to handle your volume and industry nuances. This model removes the trial and error approach that often leads to rejected applications or unfavorable terms.
Our process begins with a Financial Check-Up. This isn't a generic review; it's a deep dive into your current cash flow, outstanding receivables, and future projections. We help you identify whether factoring is the right move or if a mix of working capital and purchase order financing would serve you better. By tailoring capital solutions to your specific growth goals, we ensure you aren't just getting cash. You're getting a strategic advantage that removes barriers to progress.
Expert guidance helps you skip the noise and find the right partner on the first try. In 2026, speed and precision are your greatest assets. If you're looking to diversify your funding sources, our SBA Loan Brokers New York Guide offers additional insights into long-term capital options that complement your factoring strategy. We bridge the gap between your current financial state and your future goals.
The Allen Capital Funding Advantage
We provide professional guidance to help you select between factoring, SBA loans, and equipment finance. Our partnership-driven approach focuses on removing the financial barriers that stall your progress. We've streamlined our application processes to ensure you achieve accelerated success without the typical administrative headaches. You get the benefit of our deep industry relationships and a team that's invested in your long-term viability.
Next Steps for Your Business Growth
Getting started is simple. First, prepare your accounts receivable aging report. This document gives us the clarity needed to evaluate your current liquidity and the creditworthiness of your debtors. Once you have your data ready, you can book a consultation to explore tailored capital solutions designed for your unique business model. Don't let slow-paying customers dictate your growth rate. Schedule your strategic financial consultation with Allen Capital Funding today.
Unlocking Your Business Potential for 2026
Strategic growth requires more than just high sales; it demands a reliable and scalable cash flow engine. You've seen how converting your accounts receivable into immediate liquidity can remove the barriers that slow-paying customers create. By vetting invoice factoring companies new york for industry expertise and transparent fee structures, you position your firm to capitalize on new opportunities without the weight of traditional debt. Whether you're managing a complex supply chain or expanding a healthcare practice, the right funding structure acts as a facilitator for your long-term success.
At Allen Capital Funding, we provide the professional guidance needed to navigate these financial decisions with confidence. Our brokerage model grants you access to a national network of vetted factoring partners and customized funding strategies tailored to your specific growth stage. From your initial financial check-up to final funding, our team is dedicated to your accelerated success. Don't let unpaid invoices stall your momentum. Secure Your Strategic Capital Consultation today and take the next step toward a more agile, liquid, and prosperous future. Your business is ready to scale, and we're here to help you lead the way.
Frequently Asked Questions
How do invoice factoring companies calculate their fees?
Fees are typically calculated as a discount rate based on the invoice value and the length of time it remains outstanding. Factors also consider the credit risk of your customer and your monthly volume. Some providers include additional service or transaction fees. Transparency is key here; a professional partner will provide a clear schedule of costs during your financial check-up to ensure there are no surprises during the funding process.
Is factoring considered a loan on my business balance sheet?
No, factoring is generally recorded as an asset sale rather than a liability. Since you're selling your accounts receivable at a discount, you aren't creating a new debt obligation. This helps keep your debt-to-equity ratio low, which can be advantageous when applying for other types of financing like SBA loans or equipment financing. It's a strategic way to unlock liquidity without adding balance sheet debt and preserving your borrowing capacity.
What is the difference between recourse and non-recourse factoring?
Recourse factoring requires your business to buy back the invoice if the customer fails to pay, whereas non-recourse factoring transfers the credit risk to the factor. If a debtor becomes insolvent, the factor absorbs the loss in a non-recourse agreement. Non-recourse options usually carry higher fees because the provider takes on more risk. Choosing the right risk profile depends on your industry and the reliability of your customer base and overall risk tolerance.
Can I use factoring if my business has challenged credit or is a startup?
Yes, startups and companies with challenged credit can successfully partner with invoice factoring companies new york because the focus is on the customer's creditworthiness. As long as you have creditworthy debtors, your own financial history is secondary. This makes factoring an ideal tool for new businesses that lack the multi-year track record required for traditional bank loans. It provides the capital needed to build your reputation and scale operations during critical early stages.
How long does it take to get funded by a factoring company?
Initial setup typically takes between three and five business days for due diligence and account verification. Once your account is active, daily funding for new invoices is much faster. In 2026, most professional providers offer a 24-hour turnaround for verified invoices. This speed allows you to manage urgent expenses like payroll or inventory purchases without the long wait times associated with traditional commercial lending and lengthy bank approval processes.
Will my customers know that I am using a factoring service?
Yes, in most cases, your customers will receive a Notice of Assignment (NOA) informing them to direct payments to the factor. This is a standard procedure in modern business finance and is rarely viewed negatively by professional firms. Top-tier providers act as a supportive extension of your back office. They maintain polite and professional communication with your clients to ensure the relationship remains strong while securing your cash flow and improving collections efficiency.
Can I factor only specific invoices, or must I factor all of them?
Many modern providers offer "spot factoring," which allows you to select specific invoices for funding rather than committing your entire aging report. This flexibility is perfect for businesses that only need occasional liquidity for large contracts or seasonal peaks. You should look for partners that offer no-minimum volume requirements. This ensures you only pay for the capital you actually use, keeping your overall financing costs as efficient as possible while maintaining control over your receivables.
How does factoring compare to a traditional business line of credit?
A line of credit is a debt-based tool with a fixed limit, while factoring is a scalable asset sale that grows with your sales volume. Qualification for a line of credit depends on your business's historical performance and collateral. Leading invoice factoring companies new york offer more flexibility for fast-growing firms because they prioritize the value of your current receivables. Factoring removes the ceiling on your growth by providing capital as fast as you can bill customers.


Comments