


Equipment Financing Companies in New York: A Strategic 2026 Funding Guide
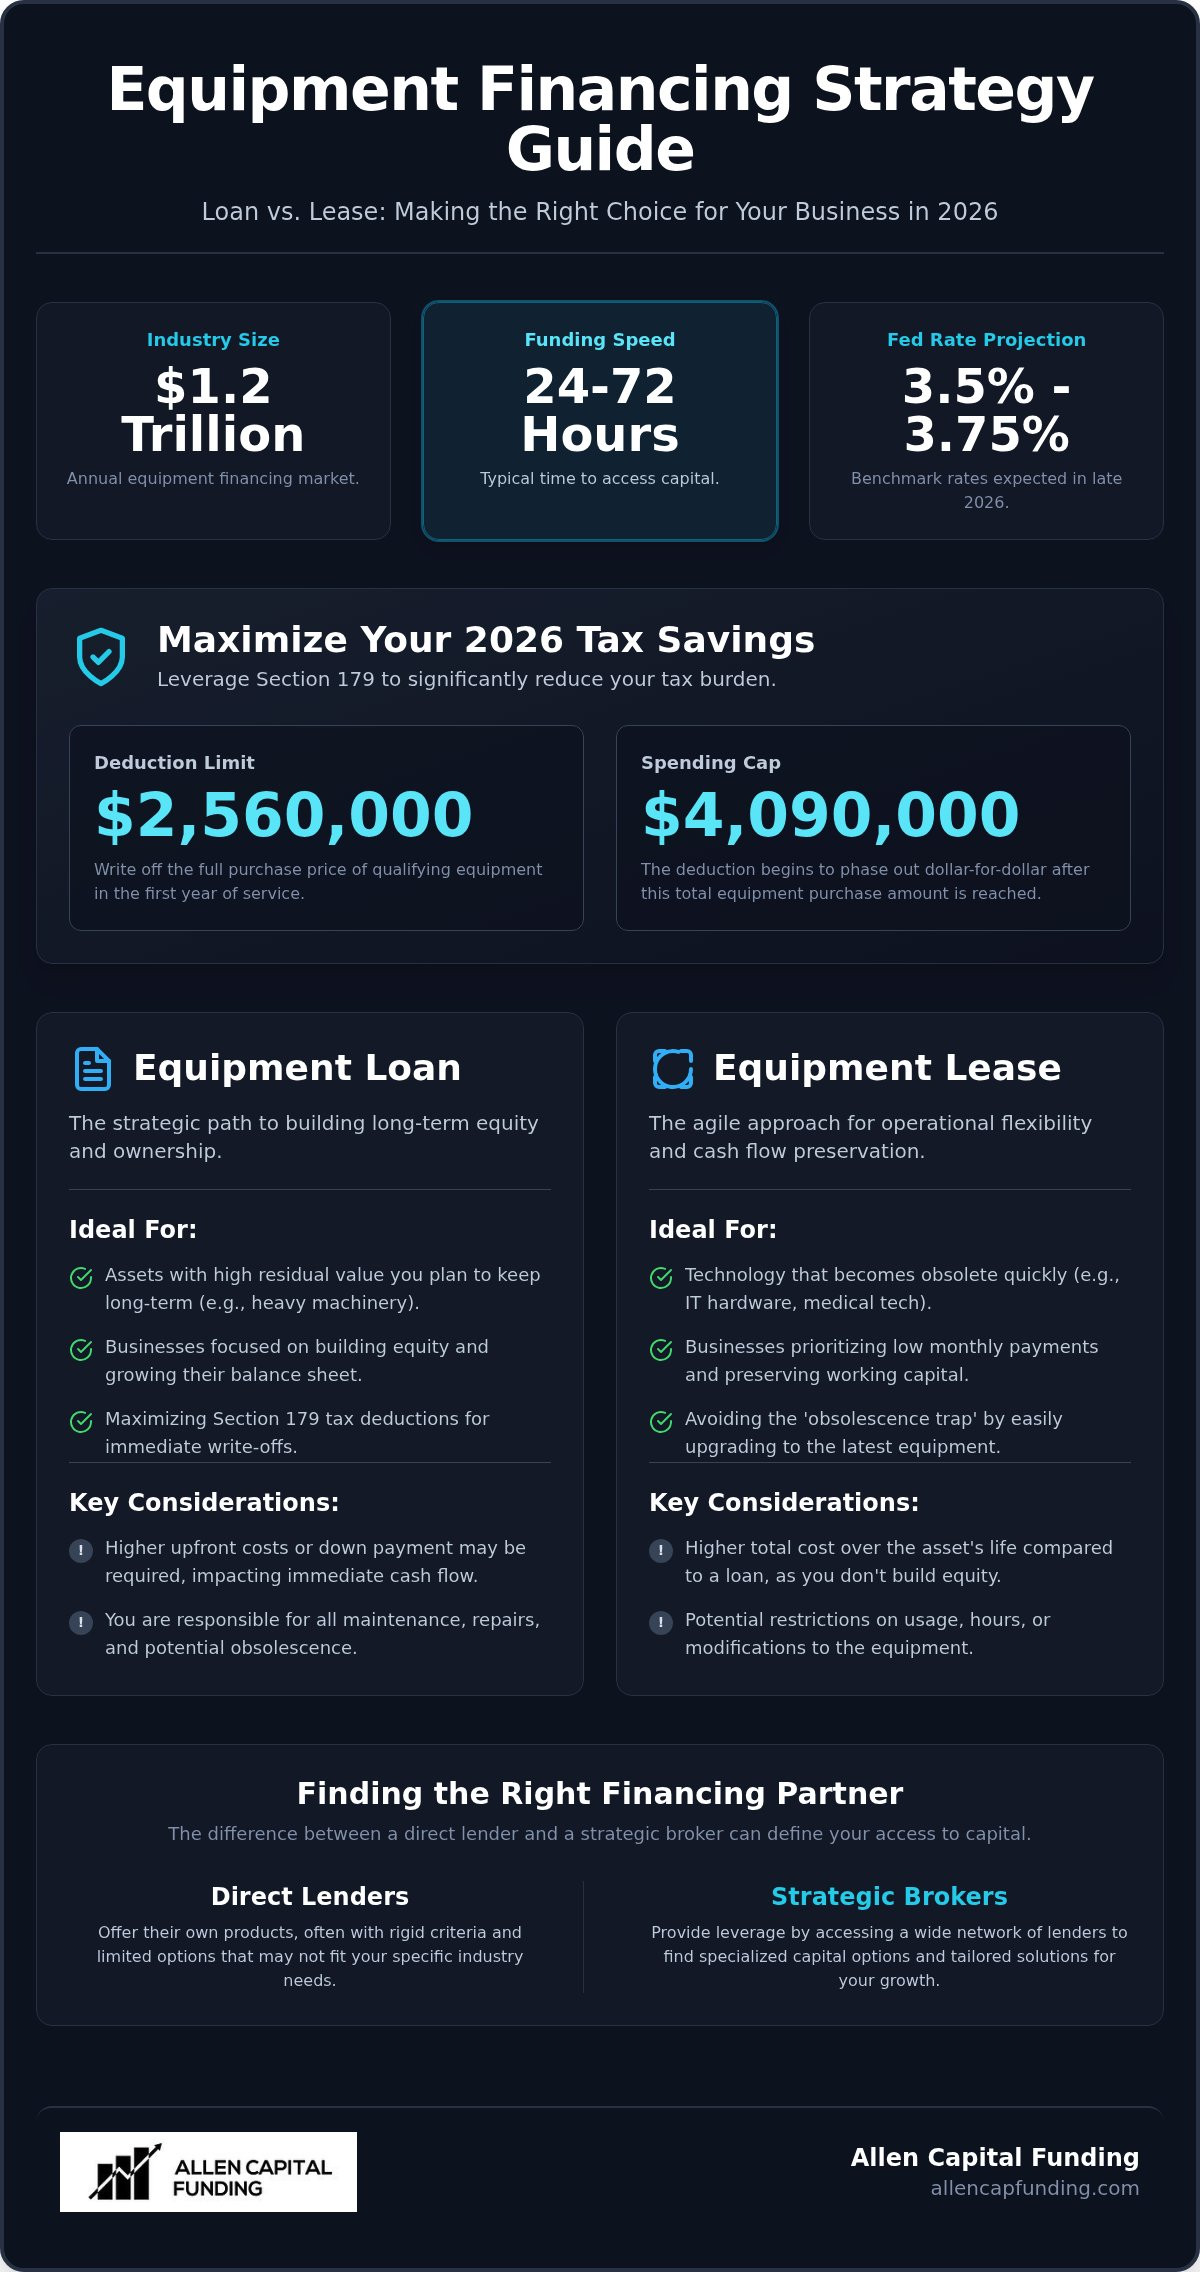
With the equipment financing industry now a $1.2 trillion a year powerhouse, it's clear that successful firms aren't just buying assets. They are leveraging strategic capital to outpace the competition. You likely recognize that waiting for interest rates to drop back to historic lows is a gamble that rarely pays off, especially with the Federal Reserve holding benchmark rates between 3.5% and 3.75% in late 2026. It is exhausting to navigate complex qualification requirements while worrying if a lender truly understands your specific industry needs.
Finding the right partner among equipment financing companies new york offers is the key to maintaining your momentum. This guide shows you how to evaluate providers and secure the essential capital to scale your operations this year. We will explore how to preserve your cash flow, access funding in as little as 24 to 72 hours, and maximize the $2,560,000 Section 179 deduction limit. You'll gain a clear roadmap to turn equipment acquisition into a competitive advantage rather than a financial burden. By the end of this guide, you will have the tools to make confident, data-driven decisions for your business growth.
Table of Contents
Navigating the Equipment Financing Landscape for New York Businesses
The commercial equipment market in 2026 demands a shift from simple procurement to strategic asset management. Businesses can't afford to let heavy machinery or medical technology sit idle while waiting for capital. New York companies face unique pressures. High operational costs and a dense competitive field mean that every dollar must work harder. This is why specialized financing structures are essential. You need a partner that understands the local economic climate while providing the muscle of national resources. Strategic equipment acquisition is now a primary driver for competitive advantage. It allows you to increase output and reduce labor costs simultaneously. When you leverage external capital, you aren't just buying a machine. You're buying the ability to outpace your rivals without draining your bank account.
Identifying the right partner among equipment financing companies new york offers is the first step toward scaling. Choosing between equipment financing companies new york provides requires looking for those that bridge the gap between local service and national reach. Allen Capital Funding acts as this strategic bridge. With our headquarters in Miller Place, we combine a deep understanding of the regional market with the ability to source specialized capital across the country. This dual approach ensures you aren't limited by local lending appetites or rigid bank criteria that don't account for your industry's specific nuances.
Identifying Your Core Equipment Needs
Start by categorizing your assets. Essential operational tools keep your doors open, while expansion tools drive new revenue. It's vital to match the financing term to the equipment's expected lifespan. If a piece of technology becomes obsolete in three years, a seven-year loan creates a financial drag. In 2026, the rapid pace of automation and AI-integrated hardware means your bottom line depends on having the most efficient tools without being tied to aging iron. Assessing these needs early allows you to choose a structure that supports your long-term ROI rather than just solving a short-term need.
The Strategic Importance of Modern Capital
Financing is a tool for cash flow preservation. By choosing a finance lease or a structured loan, you keep your working capital available for payroll, marketing, and unexpected opportunities. This approach helps you avoid the 'obsolescence trap' where you're stuck with outdated gear because you paid cash and haven't recouped the investment. 2026 is a pivotal year for industrial and medical upgrades. Businesses that secure funding now can also maximize the $2,560,000 Section 179 deduction limit. These tax benefits, combined with expert guidance, ensure that your equipment pays for itself through increased productivity and immediate tax relief.
Equipment Loans vs. Leasing: Choosing Your 2026 Strategy
Deciding between an equipment loan and a lease is a pivotal choice that shapes your company's financial trajectory in 2026. This isn't just about which monthly payment is lower. It's about how you want the asset to appear on your balance sheet and how much you want to save on taxes. Most equipment financing companies new york entrepreneurs encounter will push a standard product, but your strategy should depend on the asset's lifespan and your specific cash flow goals.
For the 2026 tax year, the IRS has set the maximum Section 179 deduction at $2,560,000. This is a massive opportunity to write off the full purchase price of qualifying equipment in the first year. The phase-out threshold begins when your total equipment purchases exceed $4,090,000. Aligning your acquisition timing with these limits is essential for maximizing ROI. Whether you choose a loan or a lease, understanding these thresholds ensures you don't leave money on the table.
When an Equipment Loan Makes Sense
When looking at equipment financing companies new york offers, you'll find that loans are ideal for assets you plan to keep for the long haul. If you are buying heavy machinery or specialized medical tools with high residual value, ownership allows you to build equity over time. These structured term loans also help you build business credit. You can even utilize the SBA 7(a) loan program to secure longer terms for major machinery purchases. For a deeper look at these ownership options, read our Commercial Equipment Loans: A Strategic Guide.
The Advantages of Strategic Leasing
Leasing offers a level of flexibility that loans cannot match, making it the preferred route for technology that evolves quickly. An operating lease, often with a Fair Market Value (FMV) option, lets you return the equipment at the end of the term. This prevents you from being stuck with obsolete gear. If you want to eventually own the asset but need to preserve cash now, a $1 Buyout lease functions like a loan with the structure of a lease. Strategic leasing can also improve your debt-to-equity ratio by keeping the liability off your main balance sheet.
Choosing the right path requires a clear view of your current standing. We recommend a financial check-up to ensure your funding choice aligns with your 2026 growth targets.
Evaluating Equipment Financing Companies: Direct Lenders vs. Brokers
Choosing between the various equipment financing companies new york businesses encounter often comes down to a fundamental choice: working with a direct lender or a strategic broker. A direct lender uses its own capital to fund your purchase. While this model is straightforward, it is also inherently limited. A direct lender can only offer you their specific products, interest rates, and terms. If your credit profile or industry doesn't perfectly align with their rigid internal criteria, you'll likely face a rejection or sub-optimal terms. They act as a single-source provider, which rarely offers the flexibility needed in a shifting 2026 economy.
Strategic brokers, like Allen Capital Funding, act as a dedicated guide between your business and a vast network of capital pools. We don't just provide a single path; we provide leverage. By positioning your business to multiple lending tiers simultaneously, a broker ensures that lenders compete for your business. This is particularly valuable when you are looking for specialized structures like the SBA 504 loan program, which is designed for major fixed assets and long-term stability. This model transforms the funding process from a simple transaction into a strategic advantage.
Why a Brokerage Model Wins in a Volatile Market
Working with a broker provides a single point of contact for multiple institutional partners. This saves you the time and frustration of managing dozens of applications. We understand how to tell your business story to the right audience, whether that is a traditional bank, a private credit fund, or a specialty equipment lessor. This approach allows us to negotiate terms that reflect your actual growth potential rather than just your balance sheet at a single moment in time. For more on how this strategy applies to government-backed funding, explore our SBA Loan Brokers New York: Strategic 2026 Guide.
Red Flags to Avoid When Selecting a Provider
Vetting equipment financing companies new york requires looking past the initial promise of low rates. You need a partner who prioritizes transparency and security. Keep an eye out for these warning signs during your search:
Hidden Fees: Be wary of providers who bury "processing," "application," or "documentation" fees in the fine print.
Inflexible Terms: Avoid contracts that don't allow for early payoff or the ability to upgrade your equipment as technology evolves.
Lack of Presence: Ensure your provider has a verifiable track record and a physical office in the United States to ensure accountability.
Allen Capital Funding removes these barriers by acting as your proactive ally. We simplify the path to progress by matching your specific needs with the most efficient capital available, ensuring your success is accelerated rather than hindered by your financing choice.
Qualification Roadmap: Securing High-Value Capital in 2026
Securing capital from equipment financing companies new york isn't just about having a high credit score. It's about presenting a cohesive financial story that proves your business can handle the debt service. The roadmap to approval starts with meticulous preparation of your Profit and Loss (P&L) statements and Balance Sheets. Lenders use these to calculate your Debt Service Coverage Ratio (DSCR). This ratio tells them if your net operating income is sufficient to cover your new equipment payments alongside existing obligations. In 2026, most lenders look for a DSCR of 1.25 or higher to ensure a safety margin.
Once your financials are in order, you must provide detailed equipment quotes and specifications. Because the asset itself serves as the primary security, the lender needs to verify its value and expected useful life. The credit review process then moves into high gear. For New York businesses, this often involves a localized review of your market position and operational history. Once approved, finalizing the deal involves signing the lease or loan agreement, after which the lender coordinates asset delivery directly with the vendor. This streamlined flow allows for funding in as little as 24 to 72 hours for many transactions.
Financial Documentation Essentials
Two years of business tax returns remain the gold standard for most lenders. They provide a historical view of your profitability and tax compliance. Small business owners should also prepare personal financial statements, as most equipment financing companies new york providers require a personal guarantee. To ensure you're ready for the scrutiny of a 2026 credit committee, we recommend a Strategic Financial Check-Up. This process identifies potential red flags in your documentation before they lead to a rejection.
Credit and Collateral Considerations
The equipment acts as your primary collateral, which often makes this funding more accessible than unsecured loans. While a FICO score of 700 or higher secures the most competitive rates, businesses with scores in the 600 to 650 range can still qualify for essential assets. Lenders also look for at least one year in business, with two years significantly improving your terms. Monthly revenue of $15,000 or more is typically required to demonstrate consistent cash flow. If you're ready to move forward, our team can help you apply for equipment financing and secure your 2026 growth tools.
Allen Capital Funding: Your Strategic Partner for Growth
Selecting a provider among the various equipment financing companies new york offers requires more than just comparing interest rates. It requires a partner who acts as a strategic bridge between your current state and your 2026 growth goals. Allen Capital Funding provides this bridge by offering expert guidance that simplifies the often complex lending environment. We don't just facilitate a single purchase. We help you build a foundation for total capital health. This includes integrating vital tools like Credit Lines and SBA Loans to ensure your business stays liquid and resilient as you scale. Our solution-focused approach removes the barriers to progress that often stall industrial and medical expansions.
A Partnership-Driven Approach to Lending
We believe in moving from a transactional mindset to a strategic one. A transaction is a one-time event, but a strategic partnership supports your business through every stage of its lifecycle. Our roots in Miller Place, NY, give us a unique perspective on the regional challenges business owners face, yet our reach is national. This allows us to deliver specialized capital solutions that local banks often cannot match. By focusing on Asset-Based Lending for Small Business, we help you unlock liquidity already sitting on your balance sheet. This proactive stance prepares you for high-stakes acquisitions without compromising your daily operational stability.
Accelerating Your Success with Tailored Capital
Efficiency is the hallmark of our consultation process. When you need to scale, waiting weeks for a credit decision isn't an option. We've streamlined the application to funding timeline so you can secure assets and start generating ROI immediately. Many businesses choose Allen Capital Funding because we provide a steady, reliable hand throughout the process. We understand the urgency of financial decision-making in 2026. Our goal is to act as a facilitator, removing the friction often found in traditional lending environments. You deserve a solution-focused ally who is deeply invested in your success. If you're ready to secure the capital needed to outpace the competition, start your tailored funding journey today. Our team is ready to provide the professional confidence and expert guidance you need to win.
Accelerating Your Business Potential in 2026
Strategic equipment acquisition is the engine of business growth. By aligning your funding choice with your operational goals, you transform debt into a powerful asset. Whether you're leveraging the $2,560,000 Section 179 deduction or navigating the broker versus direct lender landscape, your focus should remain on long-term ROI. Identifying the right partner among equipment financing companies new york offers ensures you have the support needed to navigate high interest rates and complex requirements.
Allen Capital Funding stands ready to act as your dedicated guide. We offer expert guidance from funding specialists and provide access to national lending networks from our NY headquarters. Our fast, streamlined application and closing processes remove the barriers between your current state and your future success. Secure your strategic equipment funding with Allen Capital Funding today. Your next stage of growth is within reach. We're here to help you unlock your business's full potential.
Frequently Asked Questions
What are the current equipment financing rates in New York for 2026?
Current rates for 2026 depend on your credit profile, time in business, and the specific asset you're acquiring. While the Federal Reserve's benchmark rate has stabilized between 3.5% and 3.75%, individual lender offers vary significantly. Strong credit profiles typically secure the most competitive terms, while used or specialty equipment may carry different rate structures. We recommend a consultation to review current market trends and identify the most cost-effective capital for your specific industry needs.
Can I qualify for equipment financing as a startup?
Startups can qualify for financing, though requirements are stricter than for established firms. Most lenders prefer at least one year in business, but two years significantly improves your approval odds and interest rate tiers. You generally need a minimum monthly revenue of $15,000. Because the equipment itself serves as collateral, some specialized equipment financing companies new york owners work with are more willing to consider newer businesses with strong personal credit or significant down payments.
What is the difference between an equipment loan and an equipment lease?
The primary difference lies in ownership and balance sheet treatment. An equipment loan allows you to own the asset from day one, building equity as you pay down the principal. In contrast, an equipment lease functions more like a rental with an option to buy at the end. Leasing often provides more flexibility for rapidly evolving technology, while loans are ideal for long-lived assets. Each option has distinct tax implications that impact your company's debt-to-equity ratio.
How does Section 179 benefit my equipment purchase this year?
Section 179 allows you to deduct the full purchase price of qualifying equipment in the year it's placed in service. For the 2026 tax year, the maximum deduction is $2,560,000. This incentive encourages businesses to invest in themselves by providing immediate tax relief. The benefit begins to phase out once your total equipment purchases exceed $4,090,000. Using this deduction can significantly lower the true cost of your acquisition while preserving your essential working capital.
What type of equipment can be financed through Allen Capital Funding?
We facilitate financing for a wide range of essential business assets across various industries. Common assets we fund include:
Medical and dental technology
Construction and heavy machinery
Commercial vehicles and trailers
Manufacturing and industrial equipment
Our national reach allows us to source capital for both new and used assets. Whether you're upgrading a single machine or outfitting an entire facility, our tailored solutions match your specific operational needs and growth targets.
How long does the equipment financing approval process take?
The timeline for approval depends on the size of the transaction and the complexity of your financial profile. For equipment loans under $250,000, the process is remarkably fast, often taking as little as 24 to 72 hours. Larger or more complex deals may require additional documentation and a deeper credit review, which can extend the timeline to several business days. Our streamlined consultation process focuses on speed and efficiency to ensure you get the capital you need without delay.
Do I need a down payment for commercial equipment financing?
Down payment requirements typically range from 0% to 20% of the equipment's total cost. Businesses with excellent credit profiles and strong histories often qualify for 100% financing with zero down. However, used equipment or specialty assets might require a down payment to mitigate lender risk. Providing a down payment can also help lower your monthly payments and improve your interest rate. We work with equipment financing companies new york providers to find the structure that best fits your cash flow.
Is a personal guarantee required for equipment loans in New York?
Most lenders require a personal guarantee from business owners with a 20% stake or more. It's standard practice for small and mid-sized businesses to ensure the lender has recourse if the company cannot fulfill its obligations. While the equipment itself acts as primary collateral, the personal guarantee adds a layer of security for the financing provider. In some cases, established firms with exceptionally strong balance sheets and high annual revenues may be able to negotiate a waiver of this requirement.


Comments