


Choosing the Right Small Business Lending Company for Strategic Growth in 2026
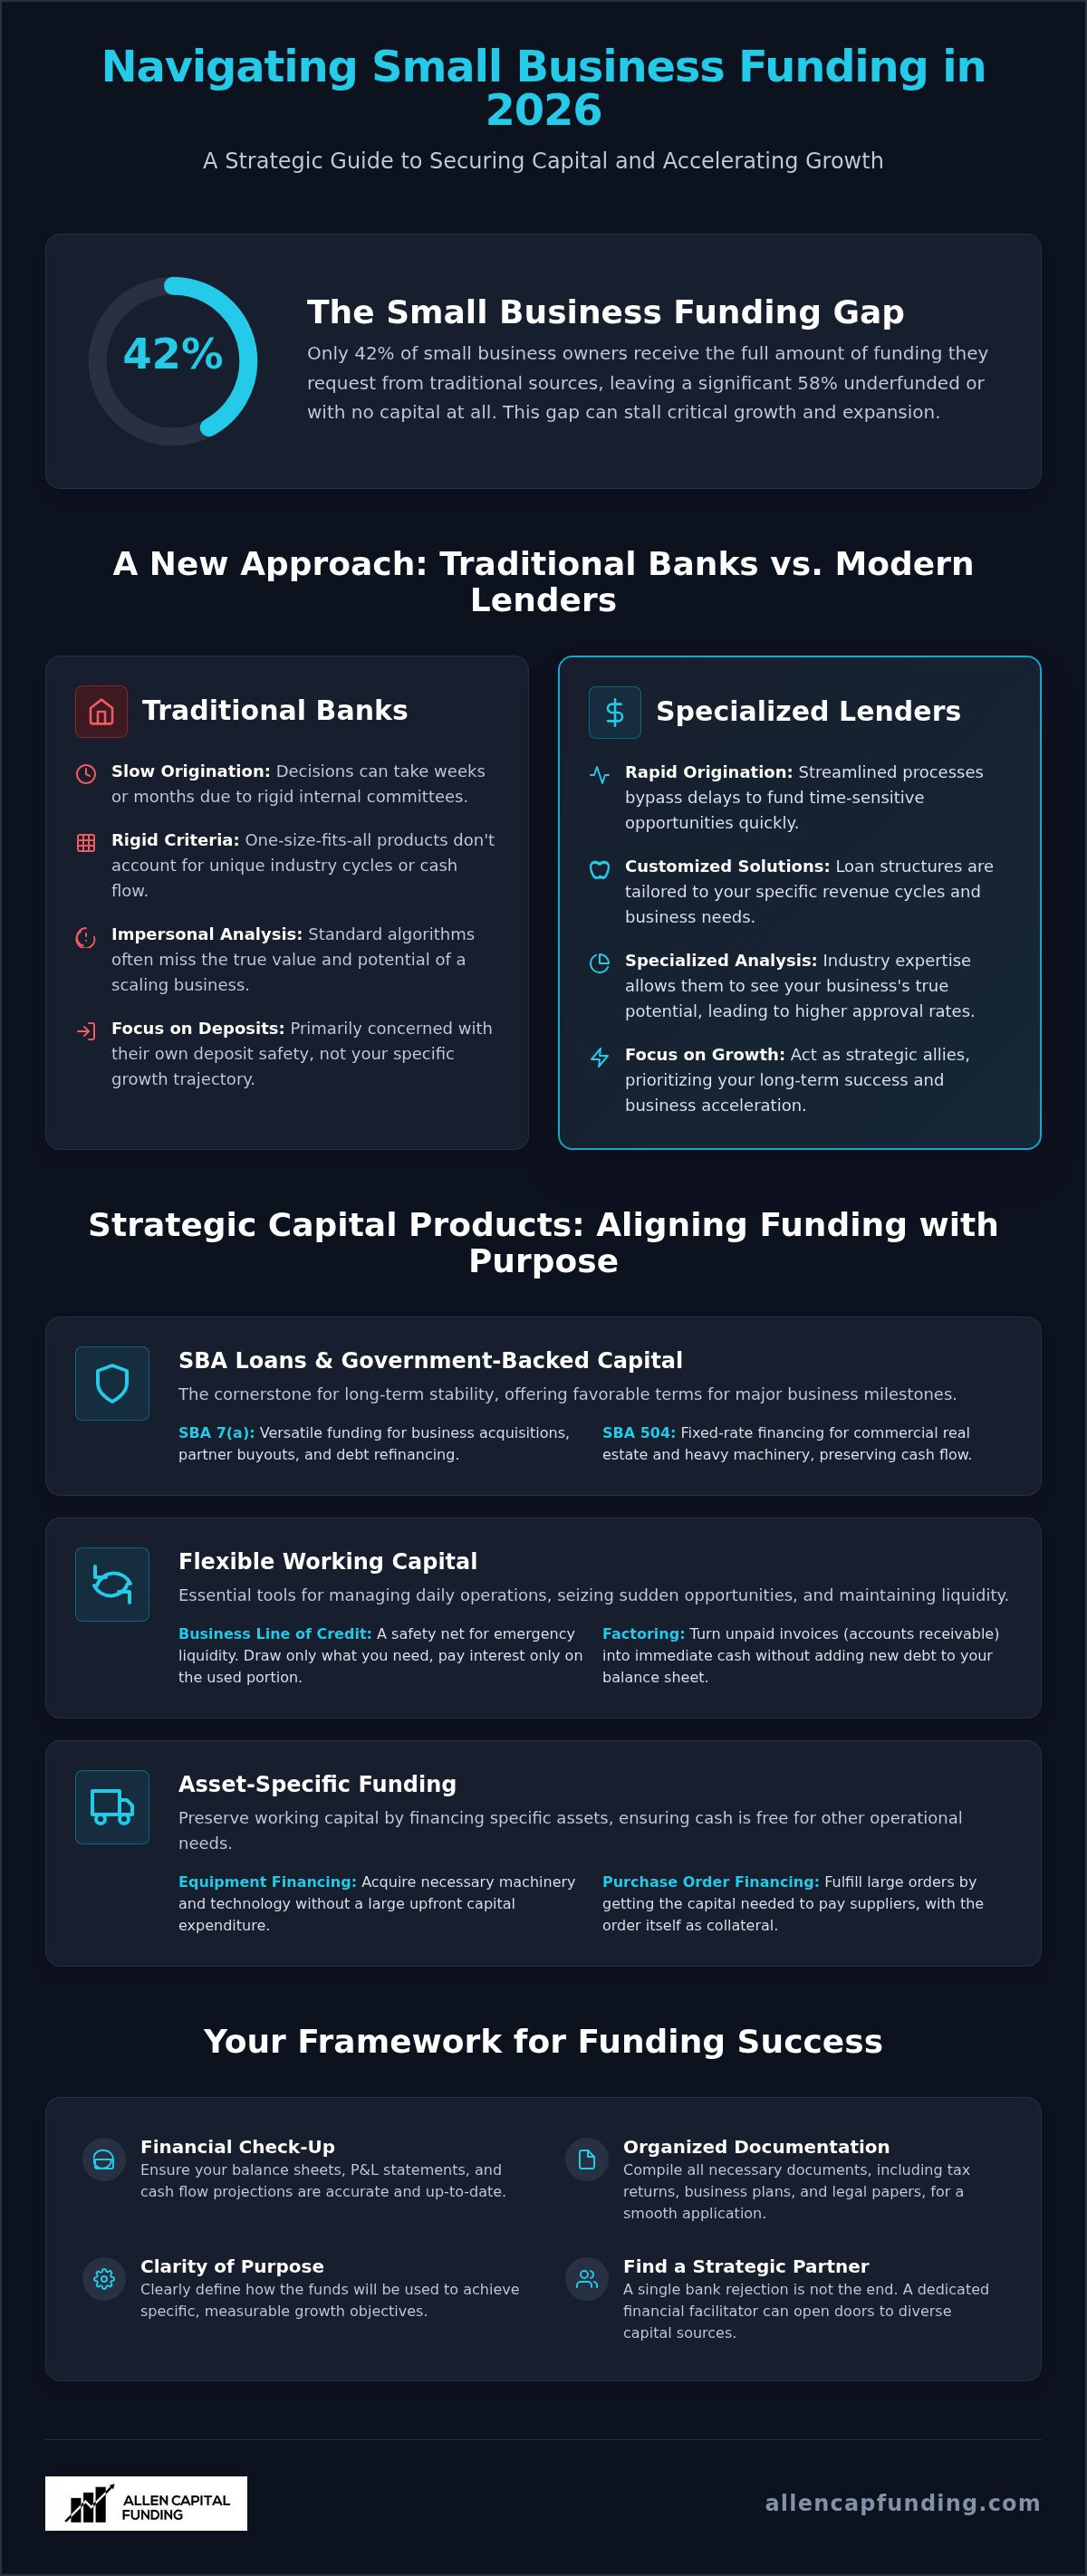
Only 42% of small business owners receive the full amount of funding they request from traditional sources. This gap often leaves entrepreneurs searching for crucial small business loans feeling stranded during critical growth phases. You've likely experienced the headache of rigid bank criteria or opaque applications that slow your momentum. It's frustrating when you have a clear vision for expansion but lack a financial partner who understands your specific industry cycles. You need capital that works for you, not against your monthly cash flow.
This article provides the clarity you need to evaluate lending companies and identify strategic capital solutions for 2026. You'll learn how to distinguish between complex products like SBA 7(a) loans and flexible options like factoring or purchase order financing. We'll explore how to calculate the total cost of capital and establish a partnership with a consultant who prioritizes your long-term success. By the end, you'll have a roadmap to secure funding that aligns with your strategic goals and accelerates your business trajectory.
Table of Contents
Defining the Modern Small Business Lending Company
A modern small business lending company isn't a traditional bank. It's a specialized firm that functions as either a direct provider of capital or a strategic intermediary. In 2026, the market has shifted significantly. More businesses now turn to non-depository lenders for faster, more agile capital draws. Traditional big box banks often prioritize their own deposit safety over your growth potential. This leads to rigid criteria that don't account for the realities of scaling a company. Specialized firms focus exclusively on business growth, offering the flexibility and industry expertise you need to stay competitive.
Lending Companies vs. Traditional Retail Banks
Speed of origination is a primary differentiator. Retail banks often rely on slow, internal committees that can take weeks or months to reach a decision. Specialized firms use streamlined origination processes to bypass these delays. They understand that growth opportunities are often time-sensitive. Customization is another key factor. Instead of offering one-size-fits-all products, these companies tailor loan structures to your specific revenue cycles. This is vital when seeking Small business financing that aligns with your cash flow. Specialized credit analysis allows these firms to see the value in your business that a standard algorithm might miss. This often results in better terms and higher approval rates for small business loans new york.
The Role of a Strategic Financial Facilitator
A strategic facilitator acts as a bridge to diverse capital markets. They aren't limited to the funds within a single depository institution. This access is crucial for growing firms with complex balance sheets or unique industry needs. They work to remove barriers to entry that often stop progress at traditional banks. Instead of acting as a gatekeeper, they act as a guide. They help you navigate different capital structures to find the one that fuels long-term success. A lending company is a strategic growth ally that transforms complex financial hurdles into clear paths for acceleration. When you're evaluating small business loans new york, you need a partner who views your success as their primary objective.
Strategic Capital Products: Navigating the 2026 Funding Landscape
Successful growth in 2026 requires more than just a lump sum of cash. It demands a strategic mix of debt and asset-based tools that protect your liquidity. Maintaining diverse funding streams ensures you can pivot when market conditions shift. Many owners struggle because they try to fund every need with a single product. For example, using a high-interest credit card for long-term equipment purchases creates unnecessary strain. Savvy entrepreneurs seeking small business loans new york understand that aligning the right product with the specific business need is the hallmark of a healthy company.
SBA Loans and Long-Term Government-Backed Capital
Government-backed options remain a cornerstone of strategic growth for established firms. SBA-guaranteed loans provide some of the most favorable terms for long-term stability. The SBA 7(a) program is highly versatile, making it the first choice for business acquisitions, partner buyouts, and debt refinancing. For those looking at commercial real estate or heavy machinery, the SBA 504 program offers fixed-rate financing that preserves your cash. Working with experienced SBA loan brokers New York businesses trust ensures your application is positioned for success in a competitive national market.
Flexible Working Capital: Lines of Credit and Factoring
Daily operations require speed and flexibility that term loans sometimes lack. A Business Line of Credit provides an essential safety net for emergency liquidity or sudden inventory opportunities. It allows you to draw only what you need and pay interest only on the used portion. If your capital is tied up in unpaid invoices, factoring offers a way to unlock that value. It turns your accounts receivable into immediate cash without adding new debt to your balance sheet. This is particularly useful when scaling quickly and waiting 30 to 90 days for payment isn't an option for your cash flow.
Asset-Specific Funding: Equipment and PO Financing
Preserving working capital is easier when you use asset-specific funding. Strategic business equipment financing lets you modernize your fleet or tech stack while keeping your cash in the bank. For companies facing large inventory surges, Purchase Order (PO) financing provides the necessary leverage. It allows you to fulfill large orders that would otherwise exceed your current cash capacity. You can even use these products simultaneously to maximize growth acceleration. A business might use an SBA loan for real estate while maintaining a credit line for operations. If you aren't sure which mix is right for you, a financial check-up can help clarify your path and optimize your capital structure.
Lending Brokerage vs. Direct Lenders: Choosing Your Path
Choosing a financial path usually involves a choice between a single-source lender and a lending solutions firm. Direct lenders, such as traditional big box banks, only offer their own proprietary products. If you don't fit their specific, often narrow risk profile, they simply decline the application. This is the "Declination Trap." Many entrepreneurs believe a bank rejection means their business isn't fundable. In reality, it usually just means that specific institution's criteria didn't align with your current situation. A lending solutions firm acts as a proactive ally, looking for ways to say "yes" through alternative channels.
A brokerage model creates a competitive environment for your loan application. Instead of asking one bank for a favor, you have multiple capital partners vying for your business. This competition often leads to better terms and more flexible structures that a single-source lender can't match. Transparency is vital in this process. A professional firm provides clarity on fees and the total cost of capital up front. They focus on the value of expert origination, ensuring complex deals get across the finish line when a standard bank would have walked away. This approach turns the funding process into a strategic advantage rather than a hurdle.
The Advantage of Multiple Funding Channels
Using a single point of contact to access a broad network of capital partners is a strategic move for risk diversification. You aren't tethered to the liquidity or the whims of one depository institution. If one source tightens its lending standards, your consultant can quickly pivot to another. This is especially important for those navigating the market for small business loans new york, where industry risk profiles vary wildly. Whether you're in manufacturing, retail, or tech, you get access to tailored funding options that match your specific growth stage. This modular approach ensures your liquidity remains intact even if one credit market shifts.
Expert Guidance and Origination Support
A dedicated team does more than just find a lender. They prepare a bank-ready application package that highlights your strengths and addresses potential weaknesses. Navigating SBA documentation is famously complex, but a dedicated specialist removes those barriers and simplifies the paperwork. For smaller needs or startups, they might even guide you toward the Microloan program to build a financial foundation. Proactive communication ensures you move from "under review" to "funded" at an accelerated pace. This expertise transforms a stressful application process into a streamlined path to capital. Having a partner who understands the nuances of small business loans new york means you can focus on running your company while they secure the resources to grow it.
Preparation Framework: Securing the Best Funding Terms
Success in the capital markets isn't just about having a profitable business. It's about being prepared. Many owners rush the process, which often leads to the high rejection rates seen in traditional banking. When you're looking for small business loans new york, your presentation matters as much as your balance sheet. Lenders need to see a clear, organized picture of your financial health before they commit their resources. Proper preparation minimizes delays and positions you for the most favorable terms available in 2026.
Documentation is the backbone of your application. You'll need at least three years of federal tax returns, current year-to-date profit and loss statements, and detailed debt schedules. A clear Use of Proceeds statement is equally vital. This document tells the underwriter exactly how every dollar will be spent and how it will generate a return. This level of transparency builds confidence and speeds up the approval process for large capital draws or unsecured lines.
The Strategic Financial Check-Up
A thorough check-up involves analyzing your debt-to-income ratios and cash flow coverage. You need to ensure your business can comfortably sustain new debt without choking its daily operations. This is also the time to identify hidden assets, such as equipment equity or high-value receivables, that can be leveraged for better terms. A strategic check-up serves as the foundation of a successful funding draw by identifying potential hurdles before they reach an underwriter's desk. You can start this process now by scheduling a Financial Check-Up with our dedicated team.
Building a Narrative for Your Business Growth
Lenders don't just invest in numbers; they invest in people and strategies. Presenting a clear growth narrative helps minimize perceived risk. Highlight your management team's experience and your company's unique market position as trust signals. When you enter your initial consultation, be ready to ask the right questions. Ask about the lender's experience in your specific industry and their typical timeline from application to funding. This proactive approach ensures you're choosing a partner who aligns with your strategic goals for small business loans new york.
Optimizing your credit profile is another critical step. Ensure your business credit reports are accurate and reflect your current standing. Reducing high-utilization balances before a large draw can significantly improve your scoring. This preparation allows you to approach the market with professional confidence. You'll know your business is positioned as a low-risk, high-reward opportunity for your capital partners.
Strategic Financial Solutions with Allen Capital Funding
Allen Capital Funding acts as a dedicated guide for small businesses across the nation. We understand that securing small business loans new york requires more than just a standard application. It requires a partner who understands the nuances of your industry and the urgency of your growth. Our team removes the complexity of the funding process. We position ourselves as a proactive ally, bridging the gap between your current state and your future goals. We don't just provide capital; we provide a structured path toward your next milestone.
Our Accelerated Success model focuses on speed without sacrificing strategic depth. We've streamlined the path from your initial consultation to the final capital draw. Unlike traditional banks that leave you waiting for weeks, we prioritize clear communication and rapid origination. This efficiency allows you to capture market opportunities as they arise. We focus on providing expert guidance that builds a sense of security. You'll work with a team that views your success as a shared objective, ensuring every term aligns with your long-term vision.
Tailored Capital for Every Business Stage
Every company has unique needs based on its specific lifecycle. Startups might need equipment financing to build a foundation, while established firms often seek real estate to expand their footprint. We facilitate complex Asset-Based Lending for Small Business to unlock liquidity hidden in your balance sheet. This includes factoring and purchase order financing for those facing rapid inventory surges. By offering customized terms, we ensure your debt structure aligns perfectly with your cash flow. This modular approach allows for sustainable growth without the pressure of rigid bank repayment schedules.
Next Steps: Book Your Strategic Consultation
Taking the next step shouldn't be a burden. We've simplified our online booking process so you can schedule a meeting when it's convenient for you. During your first consultation, our team will listen to your goals and analyze your current financial position. We'll identify the most strategic paths forward, whether that involves SBA loans or flexible working capital. You'll leave the meeting with a clear roadmap and a dedicated partner ready to facilitate your success. This partnership-driven approach is why owners looking for small business loans new york trust us to guide their expansion projects with confidence.
Accelerating Your Growth Trajectory in 2026
Securing the right capital is no longer just about finding a lender; it's about identifying a strategic ally. You've seen how the modern lending landscape favors agility and industry-specific expertise over the rigid criteria of traditional banks. By choosing a partner that offers a comprehensive suite of SBA, asset-based, and working capital solutions, you ensure your business stays liquid and ready for any opportunity. A dedicated team provides the tailored financial guidance necessary to navigate complex deals and secure favorable terms. Whether you're researching small business loans new york or looking for national expansion tools, the right preparation and partnership make all the difference.
Allen Capital Funding provides national reach with a focus on your company's strategic growth. We remove the barriers to capital, allowing you to focus on what you do best. It's time to move beyond the limitations of standard banking and embrace a solution-focused approach. Empower your business with strategic capital solutions; contact Allen Capital Funding today. We're ready to help you bridge the gap between your current success and your future goals.
Frequently Asked Questions
What is the difference between a small business lending company and a bank?
Lending companies focus exclusively on business capital and offer higher flexibility than traditional depository banks. Banks often have rigid committee-based approvals and prioritize deposit safety over growth potential. A specialized firm acts as an intermediary or direct provider of commercial capital. They tailor solutions to your specific revenue cycles rather than using a one-size-fits-all model. This approach often leads to faster funding and higher approval rates for complex deals.
How long does it typically take to get funded by a lending company?
Funding timelines vary by product, but specialized firms generally move faster than traditional banks. Working capital solutions or credit lines can often be finalized in just a few business days. Complex products like SBA loans take longer due to government documentation; however, expert origination teams still accelerate them. Using an efficient model ensures you don't miss time-sensitive growth opportunities while waiting for a committee's decision.
Can I get an SBA loan through a private lending company?
Yes, you can access SBA 7(a) and 504 programs through private lending firms that act as authorized intermediaries. These companies help you navigate the strict requirements and documentation needed for government-backed capital. They simplify the process by preparing a bank-ready application package. This is a strategic way to secure small business loans new york while benefiting from the personalized guidance of a dedicated financial consultant.
What are the requirements for an unsecured business line of credit in 2026?
Lenders typically look for strong cash flow, a solid business credit score, and at least two years of operational history. You'll need to provide tax returns and recent profit and loss statements to demonstrate your ability to service the debt. While unsecured lines don't require physical collateral, your personal credit standing remains a key factor. Maintaining a clean financial narrative is essential for securing the highest possible limits and competitive terms.
Is purchase order financing better than a traditional business loan?
Purchase order financing is better when your business faces a specific inventory surge that exceeds current cash capacity. Unlike a traditional term loan, it focuses on the creditworthiness of your customers rather than your balance sheet. This allows you to fulfill large orders without taking on long-term debt. It's a modular tool designed for rapid scaling, whereas traditional loans are better suited for long-term investments like real estate.
How does invoice factoring help with my company cash flow?
Invoice factoring turns your unpaid accounts receivable into immediate working capital. Instead of waiting 30 or 60 days for a customer to pay, you sell the invoice to a factor for a small fee. This provides an instant cash infusion to cover payroll, inventory, or operational costs. It's a strategic way to maintain liquidity without adding new debt to your balance sheet, making it ideal for fast-growing firms.
What should I look for when choosing a small business loan broker?
Look for a broker with a broad network of capital partners and deep expertise in diverse products like SBA and asset-based lending. They should offer transparency regarding fees and the total cost of capital. A good broker acts as a strategic consultant rather than just a source of cash. Ensure they provide dedicated origination support to move your application through the system at an accelerated pace.
What happens during a strategic financial check-up?
During a check-up, a consultant analyzes your debt-to-income ratios, cash flow coverage, and overall balance sheet health. They identify hidden assets that could be leveraged for better terms and spot potential hurdles before you apply for funding. This proactive review ensures your business is positioned as a low-risk opportunity. It serves as the foundation for a successful draw, whether you're seeking equipment financing or complex small business loans new york.


Comments