
SBA Loan Brokers New York: Strategic 2026 Funding Guide
Updated: Sep 19
Why do so many New York entrepreneurs treat an SBA application like a high-stakes gamble when the 2026 regulatory roadmap is already clear? You likely recognize the drain of navigating endless federal documentation only to hit a wall at a traditional bank. It's frustrating to guess which program fits your needs while requirements continue to evolve and interest rates fluctuate. Partnering with the expert SBA loan brokers New York businesses trust turns this complex maze into a streamlined capital solution that protects your time and your sanity.
We understand that your energy is better spent leading your team than decoding the new SOP 50 10 8.1 guidelines. This strategic guide reveals how specialized brokerage secures faster approval times and tailored loan structures that go beyond a simple transaction. You'll discover how a proactive financial check-up prepares you for the 165 SBSS credit score floor and positions your business for accelerated success. We're here to act as your dedicated guide, removing barriers and simplifying the path to the capital you need to scale in a competitive market.
Table of Contents
What is an SBA Loan Broker and Why Do They Matter in 2026?
An SBA loan broker acts as a professional intermediary, bridging the gap between ambitious business owners and the complex network of lenders authorized by the Small Business Administration (SBA). They don't just pass along paperwork; they function as strategic architects who structure your financial request to meet specific lender appetites. Choosing the right SBA loan brokers New York has to offer ensures you have a dedicated advocate who understands the local economic pulse while leveraging a national lender network.
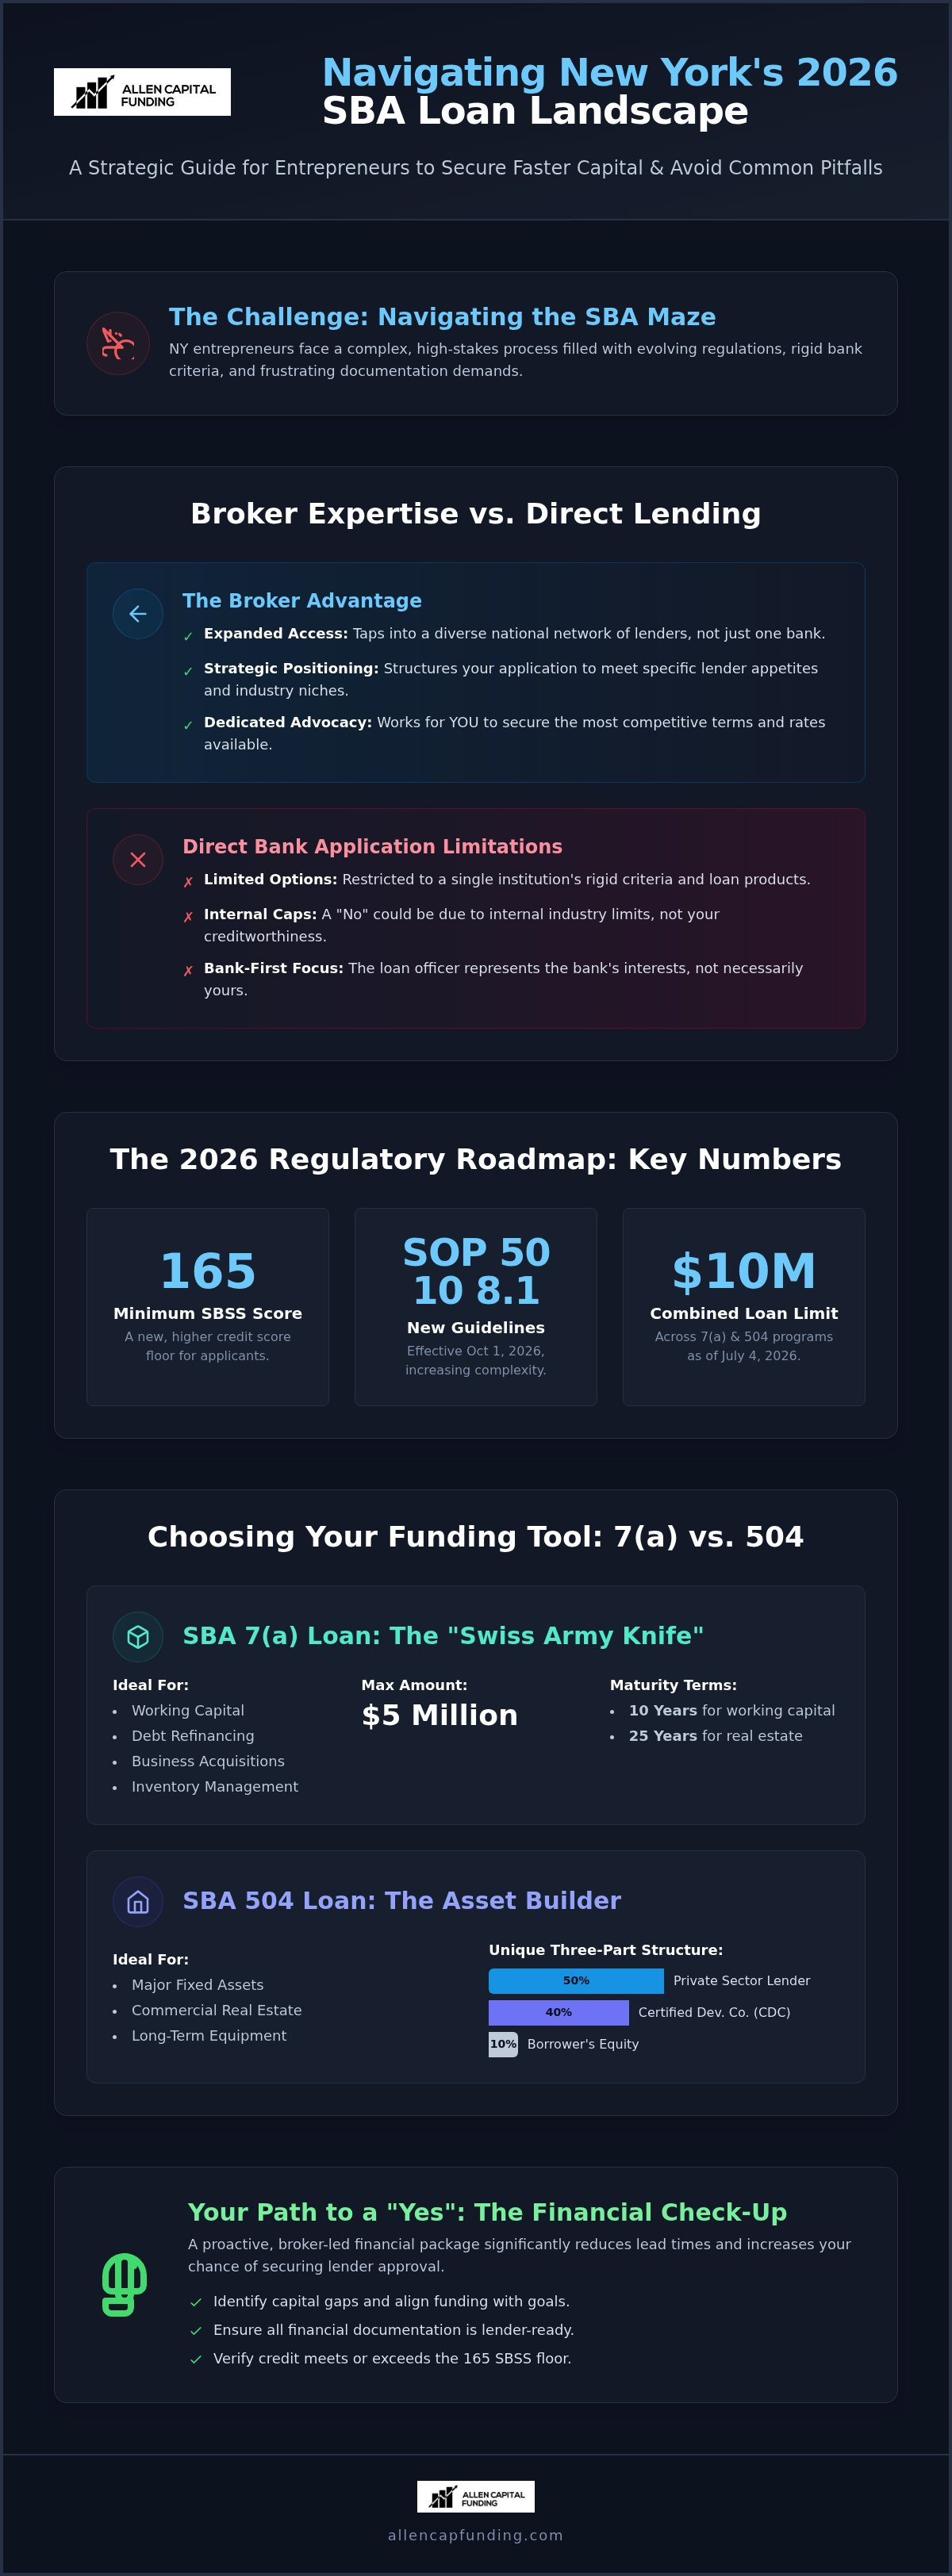
The lending landscape in 2026 is significantly more demanding than in previous years. With the implementation of SOP 50 10 8.1 on October 1, 2026, and a minimum SBSS credit score requirement of 165, the margin for error has vanished. Federal lending complexity now requires expert navigation to avoid the "red tape" that often stalls growth. Unlike a bank officer who represents a single institution's rigid criteria, an independent broker advocates for you, shopping your package to multiple sources to secure the most competitive terms and interest rates available.
The Role of an SBA Loan Specialist
Success in federal funding depends on the quality of your documentation. A specialist identifies the right lender for your specific industry niche, whether you're in manufacturing or retail, ensuring your application doesn't land on the wrong desk. They manage the exhaustive list of required forms, tax transcripts, and business valuations to prevent common filing errors that lead to automatic rejections. The specialist acts as a strategic risk-mitigator by ensuring the borrower meets stringent federal standards while providing lenders with a thoroughly vetted, high-probability application.
Brokerage vs. Direct Bank Applications
Applying directly to your local bank is a common first step, but a single "No" there doesn't mean your business isn't fundable. Banks often have internal "caps" on certain industries or loan types that have nothing to do with your creditworthiness. SBA loan brokers New York provide access to a broader network of national, regional, and community lenders who may have a higher risk tolerance for your specific sector. This expanded access is crucial if you're also considering a Business Line of Credit: The Strategic Guide to Flexible Capital in 2026 to supplement your long-term SBA funding. By utilizing a broker, you aren't limited to one bank's balance sheet; you're tapping into a diverse ecosystem of capital solutions designed for accelerated success.
Comparing SBA 7(a) and 504 Loans for Strategic Growth
Selecting between the two primary SBA loan programs depends entirely on your 2026 growth objectives. The 7(a) program serves as a versatile tool for general business needs, while the 504 program provides structured financing for major fixed assets. It's vital to understand the "guarantee" involved. The SBA doesn't lend you the money directly. Instead, they guarantee a significant portion of the loan to the lender, which reduces the bank's risk and allows them to offer you better terms in a high-rate environment. Experienced SBA loan brokers New York entrepreneurs rely on can help you determine which structure maximizes your borrowing capacity, especially now that businesses can borrow up to a combined $10 million across both programs as of July 4, 2026.
SBA 7(a) for Working Capital and Acquisition
The 7(a) loan is often called the "Swiss Army Knife" of funding because of its flexibility. In 2026, the maximum loan amount remains $5 million, with maturity terms typically set at 10 years for working capital and 25 years for real estate. This program is ideal for debt refinancing, business acquisitions, or managing inventory surges during peak seasons. If your balance sheet requires even more flexibility, you might consider Asset-Based Lending for Small Business: Unlocking Balance Sheet Liquidity in 2026. Professional SBA loan brokers New York assist in presenting these multifaceted needs to lenders to ensure your total capital solution is cohesive and covers every operational gap.
SBA 504 for Real Estate and Equipment
The 504 program uses a unique three-part structure. A private sector lender provides 50% of the project cost, a Certified Development Company (CDC) covers 40%, and the borrower contributes a 10% down payment. This program is the premier choice for owner-occupied commercial property. For 2026 compliance, non-manufacturing businesses must generally create or retain one job for every $90,000 of the CDC portion, while manufacturers enjoy a higher threshold of $140,000. This structure preserves your cash flow by requiring a lower down payment than traditional commercial mortgages and offering long-term, fixed-rate debentures. If you are ready to expand your physical footprint, you can evaluate your funding options with our team to secure a stable foundation for your business.
The Broker Advantage: Why Expertise Trumps Direct Lending
A common misconception is that applying for an SBA loan is a simple administrative task. In reality, it's a complex pitch to a skeptical audience. While direct bank officers are limited by their own institution's risk appetite, the SBA loan brokers New York businesses hire act as strategic consultants. They don't just fill out forms; they build a comprehensive "package" that addresses a lender's specific concerns before they even ask. This level of preparation often results in a "yes" where a direct application might face a "no" due to poor presentation.
Speed is a critical factor in 2026. The SBA's notorious lead times can paralyze a growing business. Brokers reduce this friction by ensuring every document is audit-ready on day one, preventing the back-and-forth requests that often add weeks to the process. They also possess significant negotiation power. With the bank prime rate at 6.75% as of September 2026, securing a lower spread on a variable-rate 7(a) loan translates into thousands of dollars in savings over a 10-year term. These long-term interest savings easily justify the brokerage fee, turning an upfront cost into a strategic investment in your company's future.
Expert Deal Structuring
Brokers focus on optimizing your Debt-Service Coverage Ratio (DSCR) before submission. They identify "red flags" in your financial history, such as a temporary dip in revenue or a credit score hovering near the 165 SBSS minimum, and provide the narrative context lenders need to move forward. By customizing the loan structure to match your business's specific cash flow cycle, they ensure the repayment schedule doesn't strain your operations during seasonal lows. This proactive approach mitigates risk for the lender while protecting your liquidity.
Access to 'Non-Bank' SBA Lenders
Traditional banks often have rigid underwriting standards that don't always align with dynamic small businesses. In contrast, non-bank SBA lenders frequently offer more flexibility because they specialize exclusively in government-guaranteed products. SBA loan brokers New York maintain pre-existing relationships with national credit officers who understand the nuances of the 2026 SBA secondary market. These connections allow your application to bypass the general intake queue, placing your file directly in front of decision-makers who value strategic growth over rigid, automated checklists.
How to Prepare Your Business for SBA Loan Approval
Preparation for an SBA loan requires more than just gathering folders of old receipts. It demands a proactive alignment of your company's financial health with the rigorous standards of 2026 federal lending. Working with experienced SBA loan brokers New York relies on can help you identify capital gaps before they lead to a rejection. This process begins with a strategic financial check-up to ensure your business is positioned for accelerated success. By identifying weaknesses early, you turn potential obstacles into manageable steps in your funding journey.
Lenders require three years of both business and personal tax returns to verify historical performance and consistency. They also look closely at your Personal Financial Statement (SBA Form 413) to assess the strength of the guarantors and the overall stability of the ownership team. Beyond history, your future projections for 2026 through 2028 must be grounded in reality and supported by a comprehensive business plan. This plan should clearly articulate how the capital will be deployed to increase revenue or improve operational margins.
The Financial Check-Up Checklist
A thorough review of your balance sheet often reveals untapped asset-based lending opportunities that can strengthen your overall application. You should verify the accuracy of your accounts receivable and aging reports to ensure your liquidity is accurately represented to the lender. It's also critical to confirm that all federal and state taxes are current or on an officially approved payment plan. For businesses struggling with back taxes or liens, US Tax Advocate Services LLC can assist in resolving these issues to ensure your application remains viable. Lenders will not move forward if there are outstanding tax liens or unresolved liabilities, as these create significant risks for the government guarantee.
Leveraging digital accounting software allows for real-time financial reporting, which is a major advantage during the underwriting phase. You must prepare your 'Use of Proceeds' statement with extreme precision, detailing exactly how every dollar will drive growth, purchase equipment, or refinance existing debt. It's vital to remember that incomplete applications are the #1 cause of SBA delays. By ensuring every field is populated and every schedule is attached, you prevent your file from being pushed to the bottom of the stack. If you're ready to begin this process with a professional eye, you can schedule your financial check-up with our dedicated team today to ensure your application is audit-ready from day one.
Partnering with Allen Capital Funding for Accelerated Success
Choosing the right partner is the final and most critical step in your funding journey. At Allen Capital Funding, we don't view ourselves as simple transaction facilitators. We act as your dedicated guide in a marketplace that often feels cold and distant. As experienced SBA loan brokers New York entrepreneurs rely on, we focus on creating a bridge between your current operations and your 2026 expansion goals. Our commitment to tailored funding options ensures that your capital structure supports long-term growth rather than just providing a short-term fix.
Our process is designed for speed and clarity. It begins with a strategic consultation where we analyze your specific needs and current financial health. From there, we move into the preparation phase, ensuring your documentation meets the new 165 SBSS score standards and SOP 50 10 8.1 requirements. We handle the heavy lifting of lender matching and negotiation, moving your file through the pipeline to a successful closing. This methodical approach respects your time and keeps your focus on running your business.
We recognize that an SBA loan is often just one piece of a larger financial puzzle. To achieve true accelerated success, you might need to integrate other solutions like Credit Lines for operational flexibility, Equipment Financing for immediate upgrades, or investment property loans from Evoque Lending. By looking beyond a single loan product, we help you build a resilient capital stack that can withstand market shifts while fueling your competitive advantage. Our goal is to provide the expert guidance you need to make informed decisions with confidence.
Our team takes a proactive approach to removing the barriers that typically stall federal applications. While we are based in Miller Place, our national reach allows us to connect you with specialized lenders across the country who understand your specific industry. We prioritize your long-term financial health over one-off transactions, ensuring that every solution we provide aligns with your broader business strategy. This combination of institutional expertise and personalized service creates a sense of security throughout the lending process.
Your Next Steps to Capital
Selecting the right capital solution depends on your current growth stage and your immediate objectives for 2026. Whether you're preparing for a large capital draw to acquire a competitor or looking to stabilize your cash flow, our strategic guidance ensures you make the right move at the right time. Don't leave your business's future to chance in a high-rate environment. You can Book an online consultation with Allen Capital Funding today to start your journey toward streamlined capital solutions and sustainable growth.
Scale Your Business with Strategic Capital
The landscape of business finance is shifting, but your growth doesn't have to stall. Success in 2026 requires a proactive approach that moves beyond simple applications. By prioritizing a thorough financial check-up and selecting the right loan structure, you position your company for long-term stability in a high-rate market. Partnering with the SBA loan brokers New York business owners rely on ensures you have a dedicated advocate navigating the updated federal requirements on your behalf.
Our team provides the expert guidance necessary to master complex federal lending while offering you direct access to a national network of SBA lenders. We don't just facilitate transactions; we act as your strategic consultant to ensure your capital stack supports your future goals. We include comprehensive financial check-ups as a standard part of our process to identify opportunities and mitigate risks before they impact your approval. It's time to move past the frustration of traditional bank rejections and embrace a path designed for speed and efficiency.
Secure your business's future with a strategic SBA loan consultation from Allen Capital Funding. We're ready to remove the barriers to your progress and help you lead your industry with confidence.
Frequently Asked Questions
What is the typical timeline for an SBA loan approval in 2026?
A typical SBA loan approval in 2026 takes between 30 and 90 days from the initial application to the final funding. This timeline varies based on the complexity of your file and the lender's current volume. Working with the expert SBA loan brokers New York entrepreneurs trust can significantly shorten this period by ensuring your documentation is audit-ready on day one. Proper preparation prevents the back-and-forth requests that often stall the process for several weeks.
Can I get an SBA loan if I have been turned down by my local bank?
You can absolutely secure an SBA loan even if your local bank issued a rejection. Individual banks often have internal restrictions or industry-specific caps that don't reflect the broader lending market. A broker provides access to a national network of lenders who may have a higher risk appetite for your specific niche. We focus on matching your business with a lender whose current criteria align perfectly with your financial profile and growth goals.
What are the current credit score requirements for an SBA 7(a) loan?
For 2026, the minimum Small Business Scoring Service (SBSS) score required to pass the automated pre-screen is 165. While this is the federal floor, most lenders also look for a personal credit score of at least 680 for all major guarantors. If your score is near these limits, our team can help you identify ways to strengthen other areas of your application, such as cash flow or collateral, to offset perceived risks.
How do SBA loan broker fees work and who pays them?
SBA loan broker fees are typically success-based and are strictly regulated by federal guidelines. These fees are often paid out of the loan proceeds at closing, meaning there's no immediate out-of-pocket cost for the borrower. By partnering with SBA loan brokers New York businesses rely on, you ensure that the fee is justified through long-term interest savings and the acquisition of more competitive terms that aren't available through direct bank applications.
Is collateral always required for an SBA-guaranteed loan?
Collateral is not always a mandatory requirement for every SBA loan, especially for smaller amounts under $50,000. However, for larger loans, the SBA generally requires lenders to take a lien on all available business assets. If those assets don't fully secure the loan, the lender may look at personal real estate. We help you navigate these requirements during a Financial Check-Up to ensure you understand exactly how your assets will be utilized in the deal.
Can SBA funds be used to purchase an existing business or franchise?
Yes, SBA 7(a) funds are frequently used to purchase existing businesses or established franchises. This program is ideal for business acquisitions because it offers longer repayment terms that help preserve your operational cash flow. You'll need to provide the seller's financial records and a clear transition plan as part of your application. Our team specializes in structuring these deals to ensure they meet the SBA's specific requirements for ownership changes and franchise eligibility.
What is the difference between an SBA loan and a traditional business line of credit?
An SBA loan is typically a long-term debt solution with a fixed maturity, whereas a traditional business line of credit is a revolving facility. SBA loans are best for large, one-time investments like real estate or equipment. Lines of credit provide the flexibility needed for short-term working capital or managing seasonal inventory gaps. We often recommend integrating both products to create a comprehensive capital stack that supports both immediate needs and long-term strategic growth.
How does the SBA 504 loan help with commercial real estate acquisition?
The SBA 504 loan helps with commercial real estate by offering a structured 50-40-10 financing model. A private lender provides 50% of the project cost, a Certified Development Company (CDC) provides 40%, and the borrower contributes a 10% down payment. This structure allows you to preserve your working capital while securing a long-term, fixed interest rate. It's the premier choice for owners who want to purchase or renovate owner-occupied commercial property in 2026.

Comments