


SBA Loan Brokers New York: A Strategic Guide to Securing Federal Business Capital in 2026
Updated: Aug 15
Why do most small business owners treat an SBA application like a lottery when it's actually a strategic hunt? You've likely heard that federal funding is the gold standard for growth, yet the mountain of paperwork and high rejection rates at traditional banks often make it feel out of reach. It's frustrating to have a clear vision for expansion or a real estate acquisition but feel stalled by rigid underwriting and confusing program choices. Partnering with experienced SBA loan brokers New York professionals changes that dynamic by aligning your business goals with federal standards before you ever submit a file.
We understand that your time is best spent running your company, not deciphering government regulations. This guide shows you how to secure the capital you need for 2026 using expert brokerage strategies that simplify compliance and maximize your chances of a successful closing. We'll explore the critical differences between 7(a) and 504 programs, the importance of our signature Financial Check-Up, and the tactical steps to move from application to funding with confidence. Your path to accelerated success starts with turning a complex process into a streamlined plan for growth.
Table of Contents
Understanding the SBA Loan Landscape in 2026
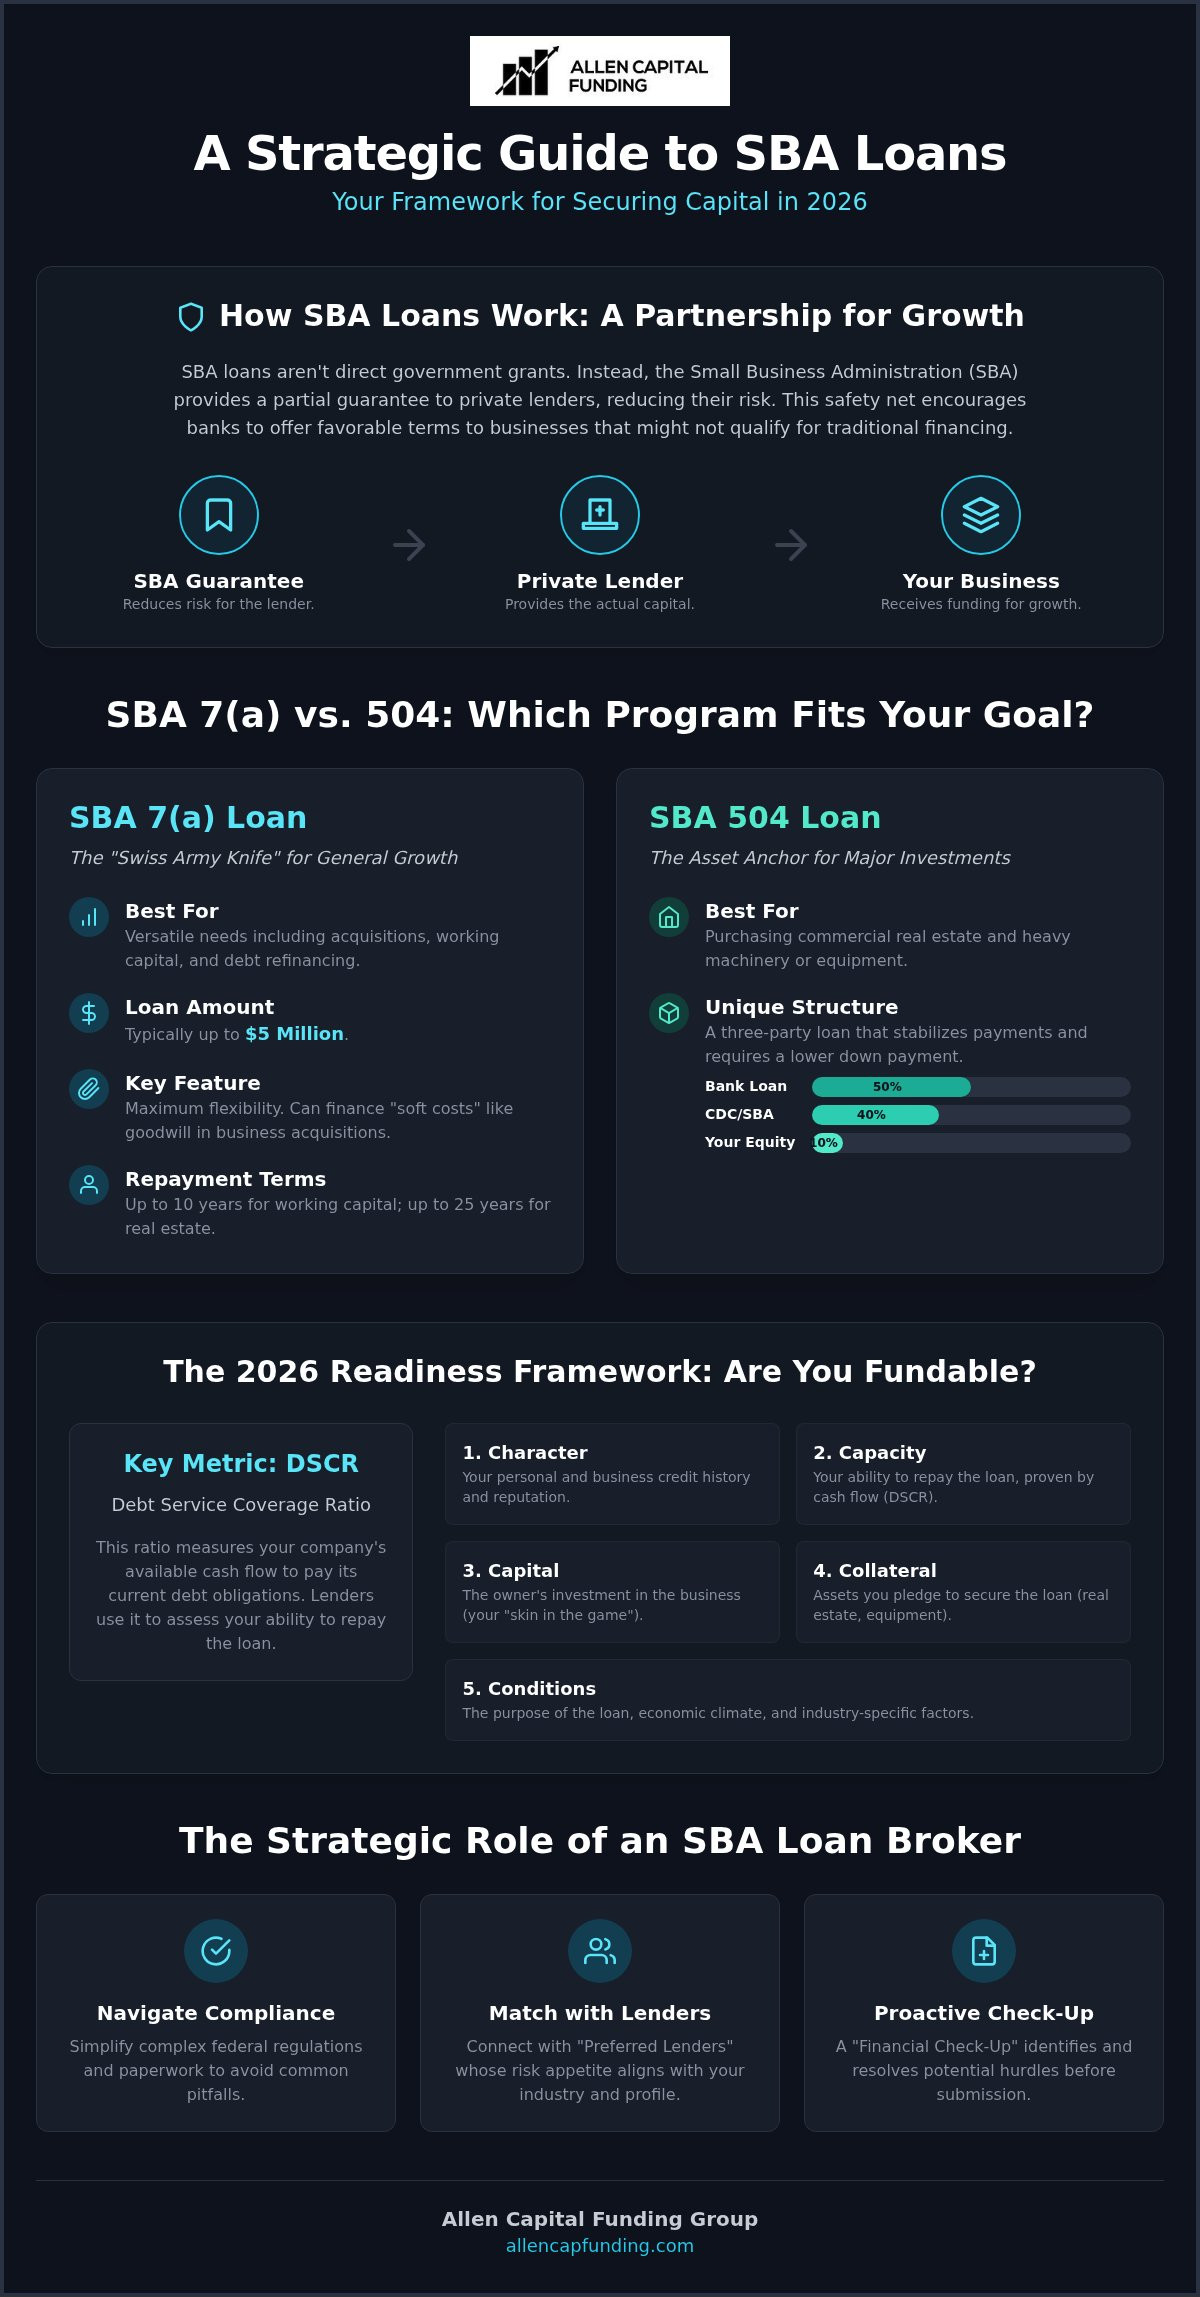
SBA loans represent a strategic partnership between the U.S. government and private lenders. In 2026, these instruments remain the backbone of small business stability. They aren't direct grants or government checks. Instead, the Small Business Administration provides a partial guarantee to the bank. This guarantee reduces the lender's risk, allowing them to offer capital to businesses that don't fit the rigid box of traditional commercial lending. Because the SBA absorbs a portion of potential losses, banks are more willing to provide competitive rates and extended repayment terms. It's a safety net that sparks growth.
The SBA sets the rules, but you still deal with a certified lender. This is where SBA loan brokers New York experts become essential. We act as the bridge between your vision and the bank's requirements. Every lender has a different appetite for risk. Some prefer medical practices while others focus on manufacturing. We ensure your business profile matches the specific preferences of a lender who understands your industry. In 2026, federal backing provides a vital buffer against market shifts, ensuring that ambitious owners can still access the capital they need to scale.
The Core Philosophy of SBA Lending
The federal guarantee allows for financial flexibility that standard commercial loans can't match. You often see longer amortization schedules and lower down payments. This preserves your company's cash flow for daily operations. One critical component is the "Credit Elsewhere" rule. To qualify, you must demonstrate that your business cannot obtain the same credit terms from non-federal sources. In 2026, SBA standards have evolved to support modern, service-based industries and tech-forward firms that lack heavy physical collateral. This shift ensures federal capital remains accessible as the economy changes. It's about empowering the "unbankable" but viable business.
Primary Use Cases for SBA Capital
Strategic growth requires capital that doesn't drain your daily reserves. Using federal backing for these goals provides a foundation for long-term scalability. Common applications for these funds include:
Business Acquisitions: Funding partner buy-outs or purchasing a competitor without depleting your liquidity.
Commercial Real Estate: Securing 25-year fixed-rate financing for owner-occupied properties to stabilize occupancy costs.
Working Capital: Covering inventory surges or payroll during rapid expansion phases with terms up to 10 years.
Equipment Financing: Purchasing high-cost machinery with low down payments to keep your technology current.
Our team treats every application as a unique puzzle. We start with a "Financial Check-Up" to ensure your paperwork is airtight before it reaches a lender's desk. This proactive approach identifies hurdles early and positions your business for a successful closing.
SBA 7(a) vs. 504 Loans: Which Strategy Fits Your Growth?
Choosing between SBA programs isn't just about getting money; it's about matching the debt structure to your specific asset. In 2026, the distinction between the 7(a) and 504 programs remains a critical pivot point for your financial strategy. One offers unmatched versatility while the other provides long-term stability for physical infrastructure. Working with SBA loan brokers New York consultants helps you determine which path preserves the most equity while fueling your expansion. It's about ensuring your capital stack supports your 2026 goals without creating unnecessary friction.
The SBA 7(a) Loan: Flexibility for General Growth
Think of the SBA 7(a) as the "Swiss Army Knife" of business lending. It's the most popular program because it covers almost any legitimate business need. In 2026, maximum loan amounts typically reach $5 million, with interest rates often structured as a spread over the Prime rate. This variable rate structure makes it highly responsive to market shifts. It's the primary vehicle for business acquisitions and partner buy-outs because it allows you to finance "soft costs" like goodwill. It also provides essential working capital and debt refinancing to help you streamline a cluttered balance sheet.
The SBA 504 Loan: Anchoring Your Real Estate Strategy
If your 2026 goals involve heavy assets, the 504 program is your primary tool. This program uses a unique three-party structure: a private bank provides 50% of the funding, a Certified Development Company (CDC) provides 40% through an SBA-guaranteed debenture, and the business owner contributes just 10%. This 10% down payment is a massive advantage for preserving liquidity compared to the 20 to 25% typically required by conventional commercial loans. The 504 program is a specialized tool for long-term, fixed-rate asset financing that anchors your business to a permanent location. It's designed specifically for purchasing land, building new facilities, or buying long-term machinery.
The choice often comes down to the rate structure. 7(a) loans are usually variable, making them flexible for shorter-term growth or acquisitions where you might refinance later. Conversely, 504 loans offer below-market fixed rates for 10, 20, or 25 years. This protects you from future interest rate hikes. If you're unsure which structure fits your five-year plan, a Financial Check-Up can clarify your eligibility and help you select the most cost-effective path. Expert SBA loan brokers New York teams ensure you don't just get a loan, but the right loan for your specific trajectory.
The Strategic Role of SBA Loan Brokers in Your Capital Journey
Applying directly to your local bank often feels like the logical first step, yet it's the primary reason many SBA applications fail. The issue isn't usually the business itself, but a fundamental misalignment of lender appetite. Every bank has internal "credit boxes" that dictate which industries they prefer and which they avoid. In 2026, these preferences shift rapidly based on economic forecasts. If you walk into a bank that is currently overexposed in retail, you'll likely receive a rejection regardless of your credit score. Experienced SBA loan brokers New York professionals eliminate this guesswork by pre-screening your file against a vast network of active lenders.
We focus on matching your business with "SBA Preferred Lenders" (PLP). These institutions have the authority to make final credit decisions without waiting for a government review, significantly shortening the timeline to funding. Our team acts as a proactive ally, packaging your loan to meet strict 2026 underwriting standards before it ever reaches a lender's desk. This preparation ensures that the narrative of your business growth is clear, compelling, and compliant. By serving as a single point of contact, we save you hundreds of hours that would otherwise be spent repeating your story to multiple banks.
Broker vs. Direct Bank: The Efficiency Gap
A direct bank application gives you one shot at a "yes." If that specific institution declines your request, you're back at square one. Working with a Small Business Loan Broker for SBA Capital provides access to national lending networks where a "no" at one bank is simply data used to find a "yes" at another. We understand the nuances of lender behavior. Some banks prioritize medical practices while others are aggressively funding franchise expansions. We navigate these preferences to find the perfect fit for your 2026 capital needs. This targeted approach preserves your momentum and protects your credit from unnecessary inquiries.
Navigating the Underwriting Maze
Underwriting is where deals often stall due to a lack of communication. We bridge this gap by clearly explaining the "three Cs" to the lender: character, capacity, and collateral. Our role is to translate your complex financial history into the specific language underwriters require. We manage the heavy lifting of the "back-and-forth" requests, ensuring that every document is provided promptly. During the appraisal and environmental phases, we act as a professional intermediary. We troubleshoot issues with third-party reports before they become deal-breakers. This level of expert guidance is essential for moving from a signed term sheet to a successful closing without the typical stress of federal financing.
Qualifying for SBA Funding: A 2026 Readiness Framework
Securing federal capital in 2026 requires more than a high credit score. Lenders now prioritize the Debt Service Coverage Ratio (DSCR) as the primary indicator of loan health. This metric compares your business’s net operating income to its total debt obligations. Most SBA lenders look for a DSCR of at least 1.25x, meaning your business generates 25% more cash than is needed to cover your debt. Understanding this ratio is the first step toward a successful application. Partnering with SBA loan brokers New York experts allows you to analyze these numbers through the lens of a lender before you officially apply. Expert SBA loan brokers New York teams ensure your file is presented to the right audience with the strongest possible financial narrative.
Modern underwriting also relies on the "Five Cs of Credit." While character and collateral remain important, capacity is the focal point for 2026. Lenders want to see that your business has the operational strength to handle new debt while maintaining existing commitments. We help you address potential weaknesses in your profile, such as past credit challenges or low capital reserves, by building a compensatory narrative. If you've faced setbacks, showing a clear trend of recovery is often more important than a perfect historical record. We focus on your current trajectory to prove you're a reliable partner for federal backing.
Financial Preparation: The 2026 Standards
Historical tax returns only tell part of the story. In today's fast-moving economy, your current-year interim financials are just as critical. Lenders use these to verify that your performance hasn't dipped since your last filing. We also focus on "add-backs," which are non-cash expenses like depreciation or one-time costs that we add back to your net income. This process reveals your true cash flow and often turns a borderline file into an approval. For a deeper look at how to position your assets, consider a Strategic Financial Check-Up to ensure your balance sheet is lender-ready.
The Business Plan and Projections
Your business plan shouldn't just be a history book. It needs to be a roadmap that explains exactly how the new capital will generate future revenue. We guide you in creating data-backed projections that reflect actual 2026 market conditions. A strong projection accounts for both growth and potential market volatility, showing lenders that you have a plan for various economic scenarios. This level of detail builds confidence and proves you're a proactive operator. If you're ready to start the process, you can apply for an SBA loan to get a clear picture of your funding options.
Accelerating Your Success with Allen Capital Funding
Allen Capital Funding operates as your dedicated guide through the complexities of business finance. We don't just submit applications; we engineer capital solutions that align with your long-term vision. As experienced SBA loan brokers New York, our team understands that every business has a unique pulse. We act as a proactive ally, removing the barriers that often stall growth and simplifying the path to federal capital. Our partnership-driven approach ensures you feel well-supported from the initial strategy session all the way to the closing table. We prioritize clarity and strategic advantage in every deal we handle.
Our multi-product approach sets us apart from traditional lenders who might only offer a single path to funding. If a federal guarantee isn't the ideal fit for your current balance sheet, we pivot quickly to find the right capital stack. We might recommend Asset-Based Lending to unlock liquidity from your existing assets or Equipment Financing to upgrade your technology without a large cash outlay. This flexibility allows us to act as a bridge between your company's current state and its future goals, regardless of market shifts in 2026.
Tailored Solutions for Strategic Growth
We customize every funding package to match your specific 2026 business goals. Whether you're targeting a competitor for acquisition or securing a permanent home for your operations, our solutions are built for speed and efficiency. We maintain a commitment to transparency, providing clear communication at every stage of the process. By working with a firm that understands the national lending landscape, you gain access to institutional-grade expertise with the personal touch of a dedicated consultant. We focus on "accelerated success" by ensuring your capital is both affordable and strategically structured.
Next Steps: Your 2026 Funding Consultation
Ready to move forward? Booking your initial strategy session is the most effective way to determine your eligibility and explore your options. To maximize our time together, have your most recent two years of tax returns and a current year-to-date profit and loss statement ready. This allows us to perform a quick "Financial Check-Up" and identify the best lending partners for your needs immediately. Don't let rigid bank requirements slow your momentum in the coming year. Schedule your expert SBA consultation with Allen Capital Funding today and take the first step toward securing the capital your business deserves.
Empowering Your Business Growth in 2026
Securing federal capital is no longer a matter of luck; it's the result of meticulous preparation and strategic alignment. By understanding the distinct advantages of 7(a) and 504 programs, you can choose the path that best protects your cash flow while supporting expansion. Success in 2026 hinges on your ability to meet modern underwriting standards like the Debt Service Coverage Ratio. Partnering with SBA loan brokers New York experts ensures your business matches with preferred lenders who are ready to fund your specific industry and goals.
We provide the expert guidance and national network access needed to move from application to closing with confidence. Our comprehensive financial check-ups identify hurdles early, giving you a competitive edge in the capital hunt. Your vision for expansion is within reach when you have the right strategic ally by your side. Secure Your Business Future: Book an SBA Loan Consultation today and take the next step toward your goals. We're ready to help you turn your 2026 objectives into reality.
Frequently Asked Questions
What do SBA loan brokers actually do?
SBA loan brokers act as strategic intermediaries who match your business with the specific lending institution most likely to approve your file. They handle the complex task of packaging your application, ensuring all federal compliance and underwriting standards are met before submission. By pre-screening your financials, they prevent you from wasting time with lenders whose current risk appetite doesn't align with your industry or growth goals.
Is it better to go direct to a bank or use a broker for an SBA loan?
Using a broker is generally more efficient because it grants you access to multiple SBA Preferred Lenders through a single point of contact. Direct bank applications often fail if that specific institution's internal credit box is closed to your industry. Expert SBA loan brokers New York teams navigate these nuances for you, finding a "yes" across a national network even if your local branch says "no."
What are the SBA loan rates expected to be in 2026?
SBA loan rates in 2026 are primarily determined by the program type and the current Prime rate. For the 7(a) program, rates are typically variable and based on a negotiated spread over Prime. The 504 program offers long-term fixed rates through its unique debenture structure. While exact percentages fluctuate with the market, these federal programs remain some of the most competitive options for small business expansion and real estate.
Can I get an SBA loan with challenged credit in 2026?
Yes, you can still qualify for funding if you demonstrate strong cash flow and debt service capacity. Lenders in 2026 prioritize your Debt Service Coverage Ratio (DSCR) over a perfect credit score. A broker helps build a compensatory narrative that explains past challenges while highlighting your current operational strength. This proactive approach turns a potential rejection into a fundable file by focusing on your business's future potential.
How long does the SBA loan process take through a broker?
The typical timeline for a successful closing ranges from 45 to 90 days, depending on the complexity of the deal. Working with a broker who utilizes Preferred Lender Program (PLP) institutions can significantly accelerate this process. These lenders have the authority to make final credit decisions internally. This eliminates the need for a separate government review, moving you from the application phase to the closing table much faster.
What is the maximum amount I can borrow with an SBA 7(a) loan?
The maximum loan amount for the standard SBA 7(a) program in 2026 is $5 million. This capital can be used for a variety of purposes including business acquisitions, working capital, and equipment purchases. If your needs exceed this limit for real estate or major fixed assets, the 504 program may provide a more suitable path with different funding structures to accommodate larger project costs.
Do SBA loan brokers charge upfront fees?
Reputable brokers generally don't charge upfront application or processing fees. Most brokerage costs are regulated by the SBA and are typically paid at the time of closing from the loan proceeds. This alignment of interests ensures that your broker is fully committed to successfully funding your project. Always verify fee structures during your initial consultation to ensure transparency and compliance with current federal guidelines.
What happens if my SBA loan application is denied by a bank?
A bank denial is often a reflection of that specific lender's internal policy rather than your business's viability. If you're rejected, an SBA loan brokers New York professional will analyze the feedback to identify the specific concern. We then pivot your application to a different lender in our network whose current appetite better matches your profile. This strategic move keeps your deal alive and maintains your growth momentum.


Comments